Buying a home is one of the largest financial decisions you will make.
The mortgage you choose can affect your monthly payment, cash required at closing, interest expense, tax considerations, future refinancing opportunities, and your overall financial position for years to come.
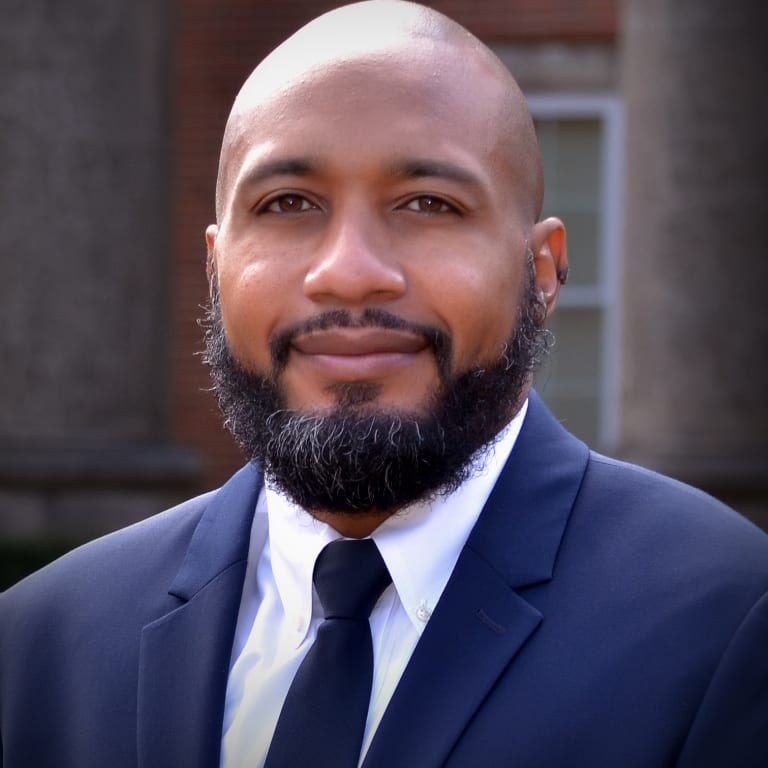
Brandon S. Broussard, Mortgage Loan Originator with Nextgen Mortgage Inc., is licensed in Massachusetts and New Hampshire (NMLS #1914798) and helps homebuyers navigate the mortgage process from the initial consultation and pre-approval through underwriting, closing, and beyond.
Brandon's approach goes beyond simply finding a loan you qualify for.
As a Certified Mortgage Planning Specialist, he helps borrowers evaluate mortgage financing as part of a larger financial strategy.
Buying a home involves several stages. Understanding what happens at each stage can make the process significantly easier and help you make better-informed decisions.
Before you start making offers, Brandon begins by learning about your financial situation and your homeownership goals.
The conversation can include:
Your income
Employment
Assets
Credit profile
Existing debts
Available funds
Desired purchase price
Expected monthly payment
Down payment
Closing-cost resources
First-time-buyer status
Future financial goals
Property type
Primary residence, second home, or investment property
Expected length of ownership
Risk tolerance
Interest-rate preferences
The objective is not simply to determine how much a lender might approve.
It is to determine what mortgage structure makes sense for you.
Your mortgage qualification is generally based on multiple factors.
Lenders evaluate areas such as:
How much qualifying income you earn and how that income can be documented and used for underwriting.
Funds available for your down payment, closing costs, reserves, and other transaction requirements.
Your credit history, scores, payment history, outstanding debts, and overall credit profile.
Your monthly obligations compared with your qualifying income.
Employment history, stability, and the nature of your income.
The property itself must satisfy the requirements of the selected loan program.
The amount you are contributing toward the purchase affects loan-to-value, mortgage insurance, pricing, and potentially your available loan options.
A mortgage pre-approval gives you a clearer understanding of your purchasing position before you begin seriously shopping for a home.
A strong pre-approval can help you:
Understand your potential price range
Determine your estimated monthly payment
Establish an appropriate down payment
Understand closing-cost requirements
Identify potential loan programs
Strengthen your offer
Move more quickly when you find the right property
Your pre-approval is not a guarantee of final loan approval.
Final approval remains subject to underwriting, verification, appraisal, title, property eligibility, documentation, and all applicable lender requirements.
The exact documentation required depends on your employment, income type, assets, credit profile, property, and loan program.
However, borrowers should generally be prepared to provide documentation such as:
Government-issued photo identification
Social Security number
Other documentation requested by the lender
Depending on your circumstances:
Recent pay stubs
W-2 forms
Federal tax returns
1099 forms
Year-to-date income documentation
Employment information
Verification of employment
Bonus or commission documentation
Overtime documentation
Retirement income documentation
Social Security or pension documentation
Award letters
Other income documentation
Self-employed borrowers may need additional documentation, potentially including:
Personal tax returns
Business tax returns
Profit-and-loss statements
Balance sheets
Business bank statements
Business ownership documentation
You may be asked for:
Bank statements
Investment account statements
Retirement account statements
Savings documentation
Gift-fund documentation, when applicable
Documentation showing the source of funds
The lender may review:
Credit report
Credit scores
Existing mortgages
Auto loans
Student loans
Credit cards
Personal loans
Other recurring obligations
If you currently own property, additional documentation may be required, such as:
Mortgage statements
Property insurance
Property tax information
Lease agreements
Rental-income documentation
Additional documentation may be required depending on your circumstances.
Provide complete, accurate, and timely documentation.
Delays frequently occur when requested documents are incomplete, outdated, inconsistent, or difficult to verify.
There is no single mortgage program that is best for every buyer.
Brandon can help you evaluate a broad range of financing options.
Conventional mortgages are loans that are not insured by the Federal Housing Administration, Department of Veterans Affairs, or U.S. Department of Agriculture.
Many conventional mortgages are eligible for purchase or securitization through the conventional conforming mortgage system associated with Fannie Mae and Freddie Mac.
These programs can offer competitive financing for qualified borrowers.
Potential advantages can include:
Competitive interest rates
Down payments potentially starting at a relatively low percentage
Options for first-time buyers
Flexible property options
Conventional mortgage insurance structures
Potentially lower mortgage insurance costs for stronger borrowers
Options for primary residences
Certain second-home and investment-property financing
Fannie Mae and Freddie Mac have different program guidelines, and eligibility depends on the borrower, property, loan characteristics, and current program requirements.
FHA loans are insured by the Federal Housing Administration.
They can be particularly useful for borrowers who may benefit from more flexible credit and down-payment requirements than some conventional programs.
Potential advantages include:
Low down-payment options
Flexible qualifying guidelines
Options for borrowers with less-than-perfect credit
Gift-fund options subject to requirements
Financing for eligible primary residences
Certain renovation financing options
FHA loans include mortgage insurance requirements and must meet FHA guidelines.
An FHA loan is not automatically the cheapest loan.
The correct comparison should consider:
interest rate + mortgage insurance + upfront costs + monthly payment + cash required + long-term cost.
VA loans are backed by the U.S. Department of Veterans Affairs and can provide significant benefits for eligible borrowers.
Depending on eligibility and circumstances, VA financing may offer:
Potentially no down payment
No monthly private mortgage insurance
Competitive interest rates
Flexible underwriting
Options for eligible primary residences
Potential seller contributions subject to VA rules
VA financing is often one of the most powerful mortgage benefits available to eligible veterans.
However, borrowers must meet VA eligibility and lender requirements, and applicable VA funding fees and other costs may apply.
USDA loans can provide eligible borrowers with financing for qualifying properties in eligible rural areas.
Potential benefits can include:
Potentially no down payment
Competitive rates
Flexible qualifying guidelines
Financing for eligible primary residences
USDA financing has geographic, income, property, and occupancy requirements.
A property being outside a major city does not automatically mean it qualifies.
Eligibility should be verified for the specific property.
Non-QM means Non-Qualified Mortgage.
Non-QM loans can provide alternative underwriting options for borrowers whose financial circumstances may not fit traditional qualified mortgage guidelines.
These programs can be especially relevant for certain:
Self-employed borrowers
Real estate investors
Business owners
High-net-worth borrowers
Borrowers with complex income
Borrowers using alternative income documentation
Real estate investors using rental income
Borrowers seeking alternative financing structures
Non-QM does not mean "no qualification."
These loans still have underwriting requirements, and the interest rate, fees, reserves, down payment, documentation, and eligibility requirements can differ significantly from conventional financing.
Depending on current lender offerings and eligibility, alternative mortgage programs may include:
Investment-property loans where qualifying rental income can play a significant role in determining the property's ability to support its debt.
Programs that may evaluate eligible self-employed borrowers using bank-statement deposits as an alternative method of documenting income.
Programs that may allow qualifying assets to be considered as a source of qualifying income under specific underwriting methodologies.
Alternative documentation options for certain borrowers who receive income primarily through 1099 compensation.
Certain programs may allow qualifying self-employed borrowers to use profit-and-loss documentation under specified guidelines.
Certain lenders offer mortgage programs for qualifying foreign-national borrowers, subject to specific requirements.
Alternative financing structures designed for qualifying real estate investors.
Non-QM products vary substantially among lenders.
Brandon can help you determine whether an alternative program may be worth exploring based on your circumstances.
An Adjustable-Rate Mortgage, or ARM, is a mortgage where the interest rate can change after an initial fixed-rate period according to the loan's terms.
ARMs are commonly described using two numbers:
5/1 ARM
7/1 ARM
10/1 ARM
The first number generally represents the number of years the initial interest rate remains fixed.
The second number generally represents how frequently the rate can adjust after that initial period.
Some ARM structures may use different adjustment frequencies, such as:
5/6 ARM
where the initial rate is fixed for five years and then may adjust every six months.
An ARM generally has three important components:
The introductory interest rate.
A benchmark used in determining future adjustments.
A percentage added to the index to determine the fully indexed rate.
The loan also typically contains caps that limit how much the rate can change.
These may include:
Initial adjustment cap
Subsequent adjustment cap
Lifetime cap
The exact structure depends on the loan.
An ARM may be worth considering when:
You expect to move before the initial fixed period ends
You anticipate refinancing
You want a lower initial payment
You expect your financial situation to change
You understand and accept future rate risk
The ARM's long-term economics make sense for your situation
But an ARM should never be selected simply because the initial rate is lower.
You should understand:
What happens if rates rise?
What will your payment become?
Can you comfortably afford the maximum potential payment?
What happens if you cannot refinance?
That is where mortgage planning becomes important.
A mortgage buydown involves paying additional money at closing—or having an eligible party contribute funds—to reduce the interest rate or payment according to the applicable loan structure.
There are two major categories:
Permanent Buydown
Temporary Buydown
A permanent buydown generally involves paying discount points to reduce the mortgage interest rate for the entire term of the loan, subject to the applicable lender's pricing and requirements.
For example, a borrower may pay points at closing in exchange for a lower interest rate.
The potential benefits include:
Lower monthly principal and interest payment
Lower interest expense over time
Greater payment stability
Potential long-term savings
The key question is:
If paying points costs $8,000 and saves $200 per month, the simple break-even period would be:
$8,000 ÷ $200 = 40 months
If you expect to keep the mortgage substantially longer than the break-even period, the permanent buydown may deserve consideration.
If you sell or refinance before reaching the break-even point, it may not be financially advantageous.
A temporary buydown reduces the borrower's effective interest rate during an initial period of the loan.
Common structures can include:
The effective rate is generally reduced by approximately:
2% during year one
1% during year two
Full note rate beginning in year three
A structure that can reduce the effective rate progressively over three years before reaching the full note rate.
The exact structure and availability depend on the loan program and lender.
Depending on the loan program and applicable rules, a buydown may potentially be funded through:
The borrower
Seller contributions
Builder incentives
Other eligible interested-party contributions
Contribution limits and eligibility vary by loan program.
A seller may prefer offering a rate buydown rather than reducing the purchase price.
For example, instead of reducing the purchase price by $10,000, a seller may contribute eligible funds toward a temporary or permanent rate reduction.
The economic benefit depends on the loan amount, interest rate, contribution amount, time the buyer keeps the loan, and other transaction factors.
The best choice should be determined by comparing the actual numbers—not simply by choosing the option with the lowest initial payment.
A Certified Mortgage Planning Specialist approaches mortgage financing as part of a broader financial strategy.
Instead of asking only:
"What loan can you qualify for?"
Mortgage planning asks:
"How should your mortgage fit into your overall financial objectives?"
This can involve examining:
Purchase price
Down payment
Interest rate
Monthly payment
Cash reserves
Closing costs
Mortgage insurance
Debt
Future refinancing
Expected length of ownership
Equity accumulation
Tax considerations
Investment objectives
Liquidity
Risk
Long-term financial goals
Should you put 5%, 10%, 20%, or more down?
The answer isn't always simply "put down as much as possible."
Keeping additional cash available may be valuable for:
Emergency reserves
Home improvements
Investments
Business needs
Other financial objectives
The correct answer depends on your circumstances.
A mortgage isn't just an interest rate.
You should evaluate:
Rate + Points + Mortgage Insurance + Fees + Closing Costs + Expected Loan Term
A slightly lower rate isn't necessarily the better deal if the upfront cost is substantially higher.
Your mortgage strategy should consider what you expect to happen after closing.
Are you likely to:
Stay for 3 years?
Stay for 10 years?
Move?
Refinance?
Pay the mortgage down aggressively?
Purchase another property?
Start investing?
Build a business?
Retire?
Your expected timeline can influence the mortgage structure that makes sense.
Home equity is valuable—but it is not the same thing as cash.
Putting a large amount of money into your down payment may reduce your monthly payment, but it can also reduce your liquid reserves.
Mortgage planning helps you consider the balance between:
equity + liquidity + payment + risk.
Instead of automatically selecting a 30-year fixed mortgage, you can compare scenarios.
For example:
30-Year Fixed
vs.
20-Year Fixed
vs.
15-Year Fixed
vs.
5/1 ARM
vs.
7/1 ARM
vs.
10/1 ARM
vs.
Temporary Buydown
vs.
Permanent Buydown
The best choice depends on your objectives, risk tolerance, financial circumstances, and expected ownership period.
Once you select a mortgage strategy, you complete the mortgage application and provide the required documentation.
The lender reviews your:
Income
Assets
Credit
Employment
Debts
Property
Loan structure
Your application then moves into processing and underwriting.
During processing, your documentation is collected, reviewed, organized, and verified.
The lender may request:
Updated pay stubs
Updated bank statements
Additional tax documentation
Employment verification
Explanations for deposits
Explanations for credit inquiries
Documentation regarding debts
Letters of explanation
Gift documentation
Additional asset documentation
Do not make major financial changes during the mortgage process without first discussing them with your mortgage professional.
Avoid opening new credit accounts, taking on significant new debt, changing jobs, moving money without documentation, or making large unexplained deposits without understanding how those actions may affect underwriting.
The lender generally needs an appraisal or other acceptable valuation method to determine whether the property supports the transaction.
The appraisal helps establish the property's market value for lending purposes.
If the appraisal comes in below the purchase price, several options may need to be considered depending on the transaction.
This is why having a strong purchase strategy before making an offer is important.
Underwriting is where the lender evaluates the complete loan file against the applicable requirements.
The underwriter reviews:
Borrower + Income + Assets + Credit + Debt + Property + Loan Program
The underwriter may issue:
Approval
Conditional approval
Additional documentation requests
Suspension
Denial
Most approved loans have conditions that must be satisfied before final approval.
Once the lender has received and approved the required documentation and all applicable conditions have been satisfied, the loan can move toward closing.
At this stage, you should understand:
Final loan amount
Interest rate
Monthly payment
Cash required to close
Closing costs
Prepaid expenses
Escrow requirements
Other final loan terms
At closing, you sign the final legal and mortgage documents, provide the required funds, and complete the purchase transaction.
Once the transaction is properly funded and recorded according to the applicable process:
Your financial circumstances can change.
Interest rates can change.
Your home's value can change.
Your income can change.
Your investment objectives can change.
That means your mortgage may deserve periodic review.
Future planning may involve:
Refinancing
Removing mortgage insurance when eligible
Changing loan structure
Accessing equity
Paying down principal
Purchasing another property
Converting a primary residence to an investment property
Evaluating future mortgage opportunities
A mortgage should be viewed as part of your broader financial picture.
Brandon brings together:
Mortgage Origination
Mortgage Planning
Real Estate Knowledge
Investment Perspective
Construction Knowledge
Property Understanding
This allows him to approach the mortgage conversation from multiple angles.
The objective isn't simply:
"Let's get you approved."
It is:
Whether you're a:
First-Time Homebuyer
Move-Up Buyer
Downsizing Buyer
Veteran
Self-Employed Borrower
Real Estate Investor
High-Net-Worth Borrower
Repeat Homebuyer
Homebuyer with Complex Income
There may be more than one way to structure your mortgage.
The challenge is determining which strategy makes the most sense for you.
Don't wait until you've found the perfect home to figure out how you're going to finance it.
Start with a conversation.
Brandon S. Broussard can help you understand your potential purchasing power, available financing options, documentation requirements, and mortgage strategies before you make an offer.
Mortgage Loan Originator
Nextgen Mortgage Inc.
Massachusetts & New Hampshire
NMLS #1914798
Certified Mortgage Planning Specialist
Mortgage financing is subject to credit approval, underwriting, property eligibility, income verification, asset verification, appraisal, and other applicable requirements. Not all borrowers will qualify for all programs. Loan programs, rates, terms, fees, down-payment requirements, mortgage insurance requirements, and underwriting guidelines are subject to change and vary by lender and borrower circumstances.
Fannie Mae, Freddie Mac, FHA, VA, USDA, and Non-QM programs have specific eligibility requirements. References to down-payment percentages, DSCR financing, adjustable-rate mortgages, buydowns, or other financing structures are educational and illustrative and do not constitute a guarantee of availability or qualification.
A mortgage pre-approval is not a commitment to lend and is subject to satisfactory verification and underwriting. Borrowers should not make major financial changes during the mortgage process without first consulting their mortgage professional.
The information presented on this page is for educational purposes and is not financial, tax, legal, or investment advice. Borrowers should consult appropriately licensed professionals regarding their individual circumstances.
Nextgen Mortgage Inc. — NMLS #1621958
Brandon S. Broussard — NMLS #1914798
Equal Housing Opportunity.
Greater New England Area
I'm a local real estate expert with experience in helping buyers achieve their real estate goals. No matter if you are a first time home buyer or have bought multiple homes, I will skillfully guide you through the process. Get a Pre-Approval and know how much you can afford.
Get Started, Get Pre-Approved ⬇
Sign in with your email address
Enter your email address
Please wait...
You’re being redirected to the page with listing data.