Your mortgage is one of the largest financial obligations you may ever have.
As your circumstances change, your mortgage may need to change with them.
Interest rates may change. Your home's value may increase. Your income may change. You may have accumulated equity. You may want to eliminate mortgage insurance, consolidate debt, access equity, change your loan term, lower your payment, or reposition your finances for the next stage of your life.
A refinance may be an opportunity to restructure your mortgage around your current financial situation and future goals.
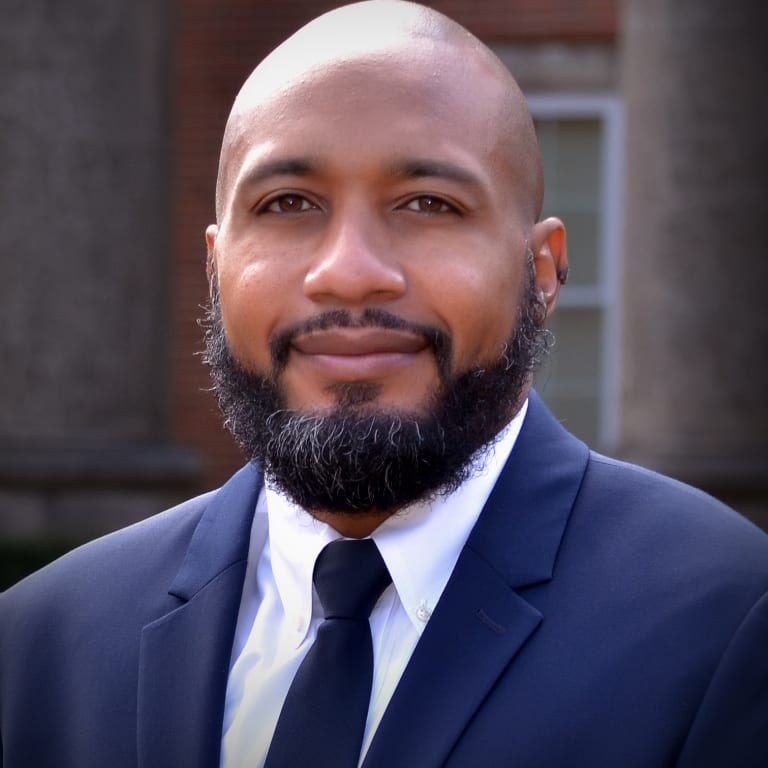
Brandon S. Broussard, Mortgage Loan Originator with Nextgen Mortgage Inc., is licensed in Massachusetts and New Hampshire (NMLS #1914798) and is a Certified Mortgage Planning Specialist.
Brandon helps homeowners evaluate refinancing from more than one perspective.
Ask:
A refinance replaces your existing mortgage with a new mortgage.
The new loan is generally used to pay off your existing mortgage, and the new loan becomes your current mortgage obligation.
Depending on your objectives, a refinance may be structured to:
Reduce the interest rate
Change the loan term
Lower the monthly principal and interest payment
Move from an adjustable-rate mortgage to a fixed-rate mortgage
Move from a fixed-rate mortgage to an adjustable-rate mortgage
Remove mortgage insurance when eligible
Access available home equity
Consolidate certain debts
Fund home improvements
Restructure your mortgage
Change the loan's repayment period
Reposition your finances for future goals
A refinance does not automatically save money.
The correct analysis should consider the new interest rate, closing costs, loan term, monthly payment, cash required, total interest, equity position, and how long you expect to keep the new mortgage.
Before recommending a refinance, Brandon begins by understanding why you are considering one.
You may want to:
Lower your payment
Lower your interest rate
Shorten your loan term
Access equity
Pay for renovations
Consolidate eligible debt
Remove mortgage insurance
Change your loan type
Move from an ARM to a fixed rate
Move from a fixed rate to an ARM
Prepare for retirement
Purchase another property
Improve cash flow
Reposition your finances
The reason for refinancing should influence the type of refinance you consider.
Before replacing your existing mortgage, we need to understand what you already have.
Important information can include:
Current loan balance
Current interest rate
Loan type
Original loan amount
Remaining term
Monthly principal and interest
Mortgage insurance
Escrow payment
Property taxes
Homeowners insurance
Current payoff amount
Prepayment provisions, if applicable
Current loan maturity date
This establishes the baseline against which the new mortgage can be compared.
Your home's current market value is extremely important in a refinance.
It can affect:
Loan-to-value ratio
Available equity
Cash-out eligibility
Interest-rate pricing
Mortgage insurance
Loan program eligibility
Maximum refinance amount
Depending on the transaction and lender, the property may require an appraisal or another acceptable valuation method.
If your home has appreciated substantially since you purchased it, the increase in value may have created additional equity.
Your approximate equity can be thought of as:
Current Property Value − Mortgage Debt = Approximate Equity
For example:
Home Value: $600,000
Mortgage Balance: $350,000
Approximate equity:
$250,000
However, not all of that equity can necessarily be accessed through a refinance.
Maximum loan-to-value limits, loan type, property type, credit, income, reserves, and other requirements determine how much equity may potentially be available.
There are several major refinance strategies.
A rate-and-term refinance generally changes the interest rate, loan term, or both without taking substantial cash equity out of the property.
Potential objectives include:
Lowering the interest rate
Lowering the payment
Shortening the loan term
Moving from an ARM to a fixed rate
Changing loan structure
Potentially removing mortgage insurance when eligible
You currently have:
30-Year Mortgage at 7.00%
You refinance into:
30-Year Mortgage at 6.00%
Your new payment may be lower, but the total economics depend on the new loan balance, closing costs, loan term, and how long you keep the mortgage.
A cash-out refinance allows a homeowner to replace an existing mortgage with a larger mortgage and potentially receive a portion of available equity as cash, subject to program and lender limits.
Possible uses may include:
Home improvements
Renovations
Debt consolidation
Investment opportunities
Business purposes, where permitted
Education expenses
Major purchases
Other financial objectives
Home Value: $600,000
Existing Mortgage: $300,000
Depending on the applicable loan program and maximum LTV requirements, you may be able to refinance for more than your current balance and receive a portion of the difference at closing.
The actual amount available depends on the program, appraisal, loan-to-value requirements, closing costs, credit, income, and other underwriting factors.
Some homeowners consider refinancing to consolidate higher-interest debt.
For example, you may have:
Credit cards
Personal loans
Other eligible debts
A refinance may potentially replace multiple payments with one mortgage payment.
But there is an important consideration:
Mortgage debt is secured by your property.
Therefore, debt consolidation should be carefully analyzed rather than viewed simply as a way to obtain a lower monthly payment.
The right comparison is:
Monthly payment + interest rate + total interest + loan term + closing costs + risk.
Homeowners may also consider accessing equity to improve their property.
Potential projects may include:
Kitchen renovations
Bathroom renovations
Roofing
HVAC
Flooring
Additions
Structural improvements
Energy improvements
General remodeling
The key question is whether the improvement supports your goals and whether using mortgage debt to fund it is financially appropriate.
Conventional refinance loans are generally not insured by FHA, VA, or USDA.
Many conventional loans are eligible for purchase or securitization through the conventional mortgage system associated with Fannie Mae and Freddie Mac.
Depending on the borrower's circumstances and property, conventional refinancing may offer:
Rate-and-term refinancing
Cash-out refinancing
Fixed-rate options
Adjustable-rate options
Potential mortgage insurance changes
Various term options
Conventional refinance eligibility depends on current program guidelines, loan limits, property type, occupancy, credit, income, equity, and other factors.
FHA offers several refinance pathways for eligible borrowers.
Potential FHA refinance structures can include:
Designed for certain existing FHA borrowers and generally intended to simplify the refinance process when applicable requirements are met.
May be used to refinance an existing mortgage under applicable FHA guidelines.
Eligible homeowners may potentially access equity through an FHA cash-out refinance, subject to FHA requirements and applicable LTV limits.
For eligible properties and transactions, FHA's 203(k) program can combine refinancing with eligible renovation financing.
FHA loans involve mortgage insurance and specific program requirements.
The correct FHA refinance strategy depends on the homeowner's existing mortgage, equity, property, occupancy, credit, and objectives.
VA refinancing can provide valuable options for eligible veterans, active-duty service members, and other qualified borrowers.
Major VA refinance pathways include:
The Interest Rate Reduction Refinance Loan, commonly known as the IRRRL, is designed for certain existing VA-backed mortgage borrowers who want to refinance their VA loan.
Potential objectives can include:
Lowering the interest rate
Changing loan terms
Potentially lowering the monthly payment
Eligibility and VA requirements apply.
Eligible borrowers may also be able to access home equity through a VA cash-out refinance, subject to applicable requirements.
VA refinancing can be especially valuable when the homeowner's existing financing no longer represents the best available strategy.
USDA provides refinance options for eligible borrowers and properties.
Depending on the applicable USDA program, refinance options may include streamlined or non-streamlined structures.
Eligibility can depend on:
Existing USDA financing
Property eligibility
Occupancy
Income
Loan characteristics
Current USDA guidelines
USDA refinance programs are designed for qualifying properties and borrowers and have specific program requirements.
Non-QM means Non-Qualified Mortgage.
Non-QM refinancing can provide alternative financing options for borrowers whose income, assets, property, or financial circumstances may not fit traditional underwriting.
Depending on lender availability, Non-QM refinance programs may include:
Certain self-employed borrowers may qualify using bank-statement documentation rather than relying exclusively on traditional tax-return income calculations.
Certain programs may allow eligible assets to be considered as a source of qualifying income under specified underwriting methodologies.
For eligible investment properties, qualifying rental income may play a significant role in determining the property's ability to support the new debt.
Certain lenders offer alternative documentation approaches for eligible borrowers receiving 1099 income.
Certain self-employed borrowers may qualify using eligible profit-and-loss documentation.
Some lenders offer refinance programs for eligible foreign-national borrowers.
Alternative financing may be available for qualifying investment properties and real estate investors.
Non-QM does not mean "no documentation" or "no underwriting."
These programs still have requirements and may carry higher rates, fees, reserves, or other costs than conventional financing.
An Adjustable-Rate Mortgage may be appropriate for certain borrowers who understand and accept future interest-rate risk.
Common ARM structures include:
Initial fixed-rate period followed by annual adjustments.
Five-year initial fixed period followed by annual adjustments.
Seven-year initial fixed period followed by annual adjustments.
Ten-year initial fixed period followed by annual adjustments.
Five-year initial fixed period followed by adjustments every six months.
Seven-year initial fixed period followed by adjustments every six months.
Other ARM structures may be available depending on the lender and loan program.
An ARM generally uses:
INDEX + MARGIN = FULLY INDEXED RATE
The loan also generally contains adjustment caps that limit how quickly the interest rate can change.
Important components include:
Initial fixed-rate period
Index
Margin
Initial adjustment cap
Subsequent adjustment cap
Lifetime cap
Adjustment frequency
Before choosing an ARM, you should understand the potential payment under higher-rate scenarios.
An ARM may be worth considering if:
You expect to move within the initial fixed period
You anticipate refinancing again
You want a lower initial payment
You have a strong understanding of future rate risk
You expect your financial circumstances to change
The ARM's total economics make sense
The initial rate should never be the only factor.
What happens if rates rise?
What is the maximum potential rate?
What could my payment become?
Can I comfortably afford that payment?
What happens if I cannot refinance later?
A mortgage buydown can reduce the borrower's interest rate or effective payment in exchange for an upfront cost or eligible contribution.
There are two primary approaches:
Permanent Buydown
Temporary Buydown
A permanent buydown generally involves paying discount points to reduce the mortgage interest rate for the life of the loan.
For example:
Without points: 6.50%
With points: 6.125%
The actual pricing depends on the lender and market conditions.
The benefit is a lower rate for the duration of the mortgage.
But the borrower must compare:
Upfront cost vs. monthly savings.
Suppose:
Cost of points: $6,000
Monthly savings: $150
Approximate break-even:
$6,000 ÷ $150 = 40 months
If you keep the loan longer than the break-even period, the buydown may potentially provide greater value.
If you sell or refinance before reaching the break-even point, the upfront cost may not be recovered.
A temporary buydown reduces the effective interest rate for a limited initial period.
The effective rate is generally reduced by approximately:
2% in year one
1% in year two
Full note rate beginning in year three
The effective rate may be reduced progressively over three years before reaching the full note rate.
The exact structure depends on the loan program and lender.
Depending on applicable rules and loan-program requirements, eligible buydown funds may potentially come from:
Borrower funds
Seller contributions
Builder incentives
Other eligible interested-party contributions
Contribution limits apply.
Buydowns are more commonly discussed in purchase transactions, but where permitted by the applicable refinance program and transaction structure, rate-reduction strategies may be worth evaluating.
The important consideration is whether the upfront cost creates enough long-term benefit.
A Certified Mortgage Planning Specialist approaches refinancing as part of a broader financial strategy.
Instead of asking:
"What is today's refinance rate?"
The conversation becomes:
A homeowner may think they want a lower rate when the actual objective is:
Lower monthly payment
Debt consolidation
Equity access
Mortgage insurance removal
Shorter loan term
Retirement planning
Investment capital
Home improvement
Improved cash flow
Reduced interest expense
The correct strategy depends on the objective.
Refinancing costs money.
Potential costs can include:
Origination charges
Discount points
Appraisal
Credit report
Title services
Recording fees
Attorney fees
Prepaid interest
Escrows
Other closing costs
If refinancing costs $10,000 and saves $300 per month:
$10,000 ÷ $300 = approximately 33 months
That is the simple monthly-payment break-even calculation.
But a complete analysis should also consider loan term, interest expense, opportunity cost, and how long you expect to own the property.
A homeowner with 25 years remaining on an existing mortgage may refinance into a new 30-year loan.
The payment could be lower.
But the borrower may also extend the repayment period by five years.
A mortgage planning analysis can compare:
Lower payment
vs.
Total interest
vs.
Remaining term
vs.
New term
vs.
Accelerated payoff options
A lower payment does not automatically mean a lower total cost.
Cash-out refinancing can unlock equity.
But using home equity creates additional debt secured by your home.
A mortgage planner can help you evaluate:
How much should you take?
What will you use it for?
What will the new payment be?
What is the cost of the money?
Will the funds create or improve financial value?
How will this affect your long-term goals?
Instead of looking at one refinance quote, mortgage planning allows you to compare strategies.
For example:
30-Year Fixed
20-Year Fixed
15-Year Fixed
5/1 ARM
7/1 ARM
10/1 ARM
Cash-Out Refinance
Debt-Consolidation Refinance
Non-QM Refinance
The best option depends on your financial objectives.
The documentation required varies based on the borrower, loan program, property, and income type.
However, you should generally be prepared to provide:
Government-issued photo ID
Social Security number
Current address
Previous addresses, when applicable
Marital-status information where required for the application
Contact information
Potentially:
Recent pay stubs
W-2s
Federal tax returns
1099s
Employment verification
Year-to-date income documentation
Bonus documentation
Commission documentation
Overtime documentation
Pension documentation
Social Security documentation
Retirement income documentation
Self-employed borrowers may need additional documentation, potentially including:
Personal tax returns
Business tax returns
Profit-and-loss statements
Balance sheets
Business bank statements
Business licenses
Corporate or partnership documents
Ownership documentation
Year-to-date financial statements
The exact documentation depends on the loan program and underwriting requirements.
You may need:
Bank statements
Savings statements
Investment account statements
Retirement account statements
Stocks
Bonds
Other eligible assets
Documentation for large deposits
Gift documentation, where applicable
The lender may need:
Current mortgage statement
Mortgage account information
Current payoff information
Existing loan terms
Mortgage insurance information
Escrow information
Potential documentation may include:
Homeowners insurance declaration page
Property tax information
Current deed information
HOA documentation
Condo documents
Lease agreements for rental properties
Rental income documentation
Existing property-related obligations
Determine your objective.
Provide income, asset, credit, mortgage, and property documentation.
Complete the mortgage application and select the appropriate refinance strategy.
Review and acknowledge the applicable loan disclosures.
The lender verifies your financial information and prepares the loan for underwriting.
The lender obtains an appraisal or other acceptable valuation when required.
The title company or applicable closing professional verifies ownership, liens, and other title-related matters.
The underwriter evaluates the complete loan file.
Any outstanding conditions must be satisfied.
The lender provides final approval when all applicable requirements have been satisfied.
You receive the applicable final closing information and review the final loan terms and costs.
You sign the refinance documents and provide any required funds.
The new loan funds and the existing mortgage is paid off according to the transaction.
Your new payment schedule and loan terms become effective according to the new mortgage documents.
There is no guaranteed timeline.
A refinance can be affected by:
Borrower documentation
Loan complexity
Property type
Appraisal
Title
Underwriting
Income verification
Asset verification
Loan program
Lender volume
Outstanding conditions
Closing availability
Providing complete documentation quickly and responding promptly to requests can help prevent avoidable delays.
These questions are the foundation of a true mortgage planning conversation.
A refinance should not be based solely on a headline interest rate.
The right refinance strategy considers:
Your Home
Your Equity
Your Income
Your Debt
Your Cash Flow
Your Goals
Your Risk
Your Timeline
Your Future
That's the difference between simply refinancing a mortgage and planning a mortgage strategy.
Brandon S. Broussard
Mortgage Loan Originator
Nextgen Mortgage Inc.
Licensed in Massachusetts & New Hampshire
NMLS #1914798
Brandon helps homeowners evaluate refinancing opportunities through a comprehensive mortgage-planning approach.
Whether your objective is to reduce your payment, access equity, consolidate eligible debt, change your loan structure, eliminate mortgage insurance when eligible, shorten your mortgage term, or reposition your finances for the future, the first step is understanding the numbers.
Mortgage financing is subject to credit approval, underwriting, property eligibility, income verification, asset verification, appraisal or other valuation requirements, and other applicable conditions. Not all borrowers will qualify for all programs.
Fannie Mae, Freddie Mac, FHA, VA, USDA, Conventional, Non-QM, ARM, cash-out, and other refinance programs have specific eligibility requirements. Loan programs, rates, terms, fees, loan-to-value requirements, mortgage insurance requirements, closing costs, and underwriting guidelines are subject to change and vary by lender and borrower circumstances.
A refinance may or may not reduce your total cost of borrowing. A lower monthly payment may result from extending the loan term and may increase total interest paid over the life of the loan. Cash-out refinancing increases mortgage debt and may place additional debt against your home.
Buydowns, discount points, seller or other contributions, and temporary rate-reduction structures are subject to the applicable loan program, lender requirements, contribution limits, and transaction eligibility. ARM rates and payments may increase after the initial fixed-rate period and are subject to the terms, indices, margins, and caps contained in the applicable loan documents.
Non-QM programs have varying documentation, reserve, credit, property, and income requirements and may have different pricing or costs from conventional mortgage products.
The information presented on this page is for general educational purposes and is not financial, tax, legal, or investment advice. Borrowers should consult appropriately licensed professionals regarding their individual circumstances.
Nextgen Mortgage Inc. — [Company NMLS Number]
Brandon S. Broussard — NMLS #1914798
Equal Housing Opportunity.
Greater New England Area
I'm a local real estate expert with experience in helping homeowners achieve their real estate goals. My strategic marketing plan and comprehensive market analysis, will help you sell your home quickly and for the best possible price.
Get Started, Contact Me ⬇
Sign in with your email address
Enter your email address
Please wait...
You’re being redirected to the page with listing data.