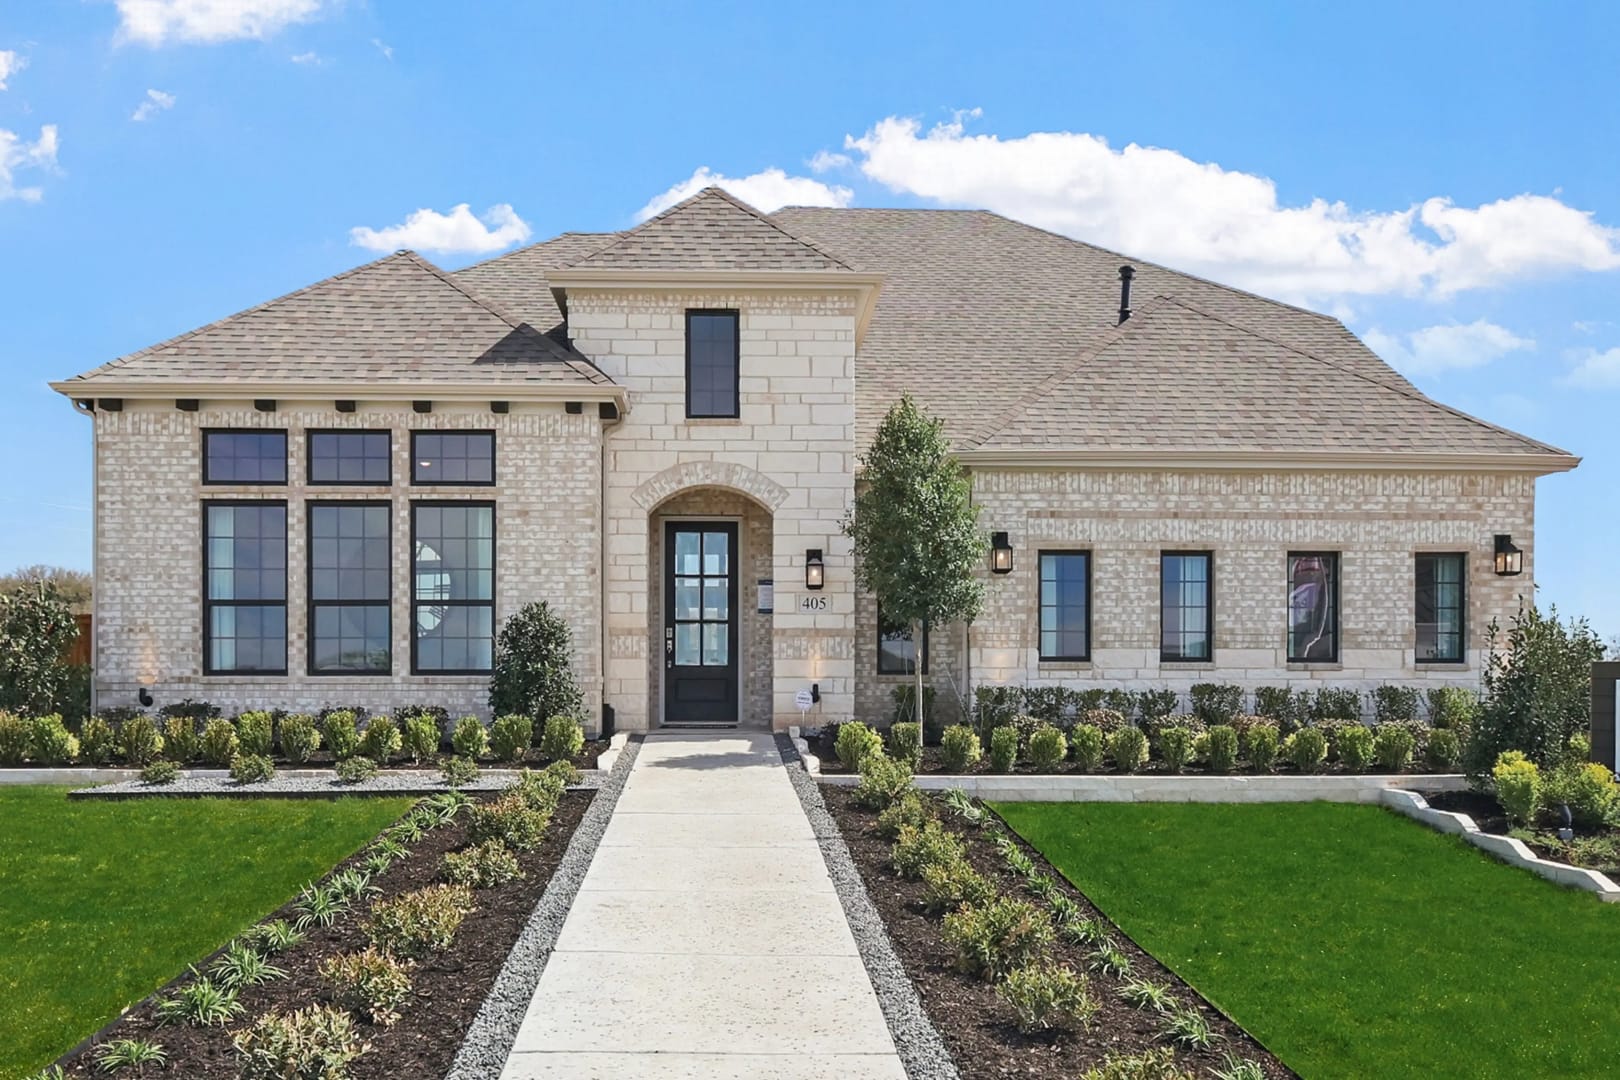
Your home is more than a building.
It may be your largest investment, your family’s primary place of residence, the place where memories are created, and one of the most important assets you own. Yet many homeowners don't fully understand what their homeowners insurance actually covers until they need to use it.
That is where the right insurance professional can make a significant difference.
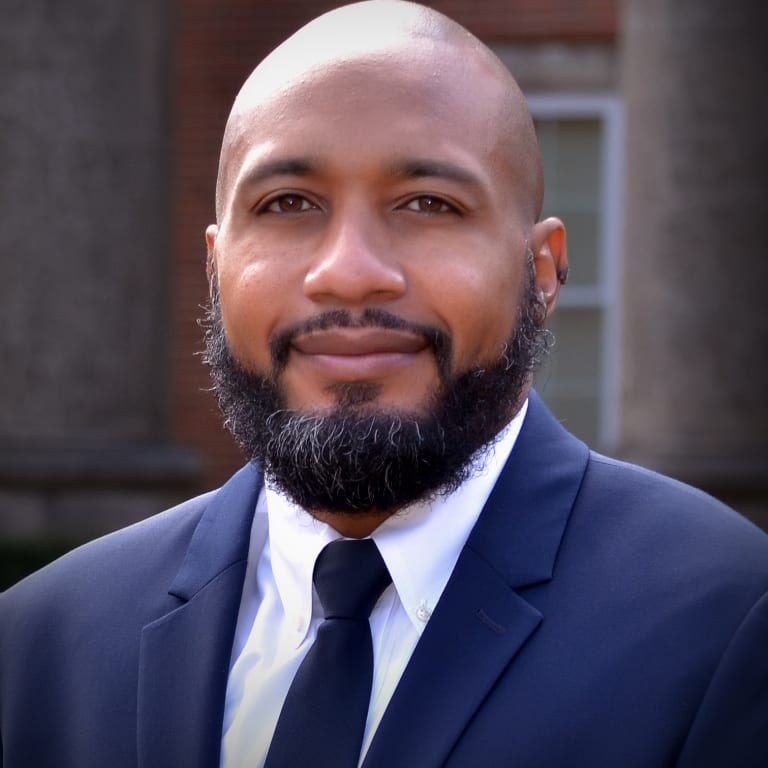
Brandon S. Broussard is a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc., helping homeowners better understand their coverage options and make informed decisions about protecting their home, personal property, liability, and financial interests.
The goal isn't simply to find you a policy.
The goal is to help you understand what you're buying, why you need it, where the potential gaps are, and how your coverage should work when you need it most.
Homeowners insurance is designed to provide financial protection against certain covered losses involving your home, personal belongings, liability, and other covered exposures associated with owning and occupying a property.
A homeowners policy can potentially protect several different areas of your financial life, including:
The physical structure of your home
Other structures on your property
Personal belongings
Additional living expenses after a covered loss
Personal liability
Medical payments to others
Certain legal defense expenses
Certain property-related risks and losses
However, homeowners insurance is not an unlimited protection plan.
Coverage depends on the specific policy, endorsements, exclusions, limits, deductibles, conditions, and circumstances of the loss.
That is why simply choosing the cheapest premium may not always produce the protection you actually need.
A typical homeowners policy is commonly structured around several major coverage categories.
Understanding these categories can help you have a much more productive conversation about your insurance.
Dwelling coverage is generally designed to protect the physical structure of your home against covered causes of loss.
This can include the home's:
Roof
Walls
Foundation, subject to policy terms
Flooring
Cabinets
Built-in appliances
Electrical systems
Plumbing
HVAC systems
Permanently installed fixtures
Other permanently attached components
One of the most important concepts homeowners should understand is that the amount of dwelling coverage is not necessarily the same as the home's market value.
Your home's market value reflects factors such as land, location, supply and demand, and comparable properties.
Insurance coverage for the dwelling is generally concerned with the cost to repair or rebuild the covered structure, subject to the policy.
That distinction can be extremely important.
Imagine purchasing a home for $600,000.
That does not automatically mean the house should be insured for exactly $600,000.
The cost to rebuild may be higher—or lower—depending on construction costs, materials, labor, architectural characteristics, local building requirements, debris removal, and other factors.
The objective is to establish an appropriate coverage amount based on the insurance policy and valuation methodology—not simply the home's purchase price.
Your property may contain structures that are separate from the primary dwelling.
Depending on the policy, this coverage may apply to certain structures such as:
Detached garages
Sheds
Fences
Certain outbuildings
Other detached structures
If you have a detached garage, workshop, pool house, significant fencing, or another structure, it is important to discuss it with your insurance professional.
A standard policy may provide some coverage automatically, but the amount and scope of coverage may not be appropriate for every property.
Your home is filled with possessions that can be surprisingly expensive to replace.
Personal property coverage may apply to covered losses involving belongings such as:
Furniture
Clothing
Electronics
Televisions
Computers
Appliances
Tools
Household goods
Sporting equipment
Certain collectibles
Certain valuables
But there is an important consideration:
Not every category of personal property necessarily receives unlimited coverage.
Certain high-value items may have special limits under a standard policy.
That can include items such as:
Jewelry
Watches
Fine art
Collectibles
Certain firearms
Silverware
Coins
High-value electronics
Other specialized property
Depending on the circumstances, an endorsement or separate scheduling arrangement may be appropriate.
"If I lost everything in my house tomorrow, would my current personal property coverage realistically be enough to replace it?"
That question can reveal coverage gaps that homeowners may not recognize.
Imagine a covered loss makes your home temporarily uninhabitable.
You may suddenly need to pay for:
Temporary housing
Hotel expenses
Increased food costs
Transportation
Storage
Other qualifying additional living expenses
Depending on the policy and circumstances, Additional Living Expense / Loss of Use coverage may help with certain increased costs associated with a covered loss.
This is one of the most overlooked portions of homeowners insurance.
People often focus on the house itself.
But if your home becomes unlivable, the financial consequences can extend far beyond repairing the building.
Homeownership creates liability exposure.
Someone could potentially be injured on your property.
A guest could fall on your stairs.
A visitor could be injured around your swimming pool.
A contractor could claim damages.
A covered incident could result in a lawsuit.
Personal liability coverage is generally designed to provide protection for certain covered claims alleging bodily injury or property damage for which you may be legally responsible, subject to the policy's terms, exclusions, and limits.
It may also provide certain legal defense protection.
Your home isn't just an asset.
You are also exposed to liability because you own and occupy property.
A lawsuit can potentially put more than the value of the physical property at risk.
That makes liability coverage an important part of a comprehensive homeowners insurance strategy.
Many homeowners policies include a medical payments coverage component.
This coverage may help pay certain medical expenses when someone is injured on your property, subject to the policy's terms and limits.
It is generally different from personal liability coverage because it can apply in circumstances where determining legal liability may not be necessary in the same way.
The specific circumstances and policy requirements matter.
Homeowners insurance can provide broad protection, but it is important to understand that policies generally cover specified causes of loss or risks according to the policy language.
Depending on the policy form, coverage can potentially address losses associated with events such as:
Fire
Smoke
Certain wind damage
Certain hail damage
Theft
Vandalism
Certain falling objects
Certain accidental water-related losses
Certain freezing-related losses
Certain sudden and accidental damage
Other covered causes of loss
The exact coverage depends on the policy.
Never assume an event is covered simply because you have homeowners insurance.
The policy language, exclusions, conditions, endorsements, deductibles, and facts surrounding the loss all matter.
One of the most important parts of purchasing insurance is understanding what isn't covered.
Common exclusions or limitations may include certain losses caused by:
Flood
Earth movement
Certain types of water damage
Wear and tear
Maintenance issues
Neglect
Certain pest damage
Certain mold-related losses
Intentional acts
Certain sewer or drain backup situations
Certain business activities
Other excluded causes of loss
The exact exclusions vary by policy.
A standard homeowners policy generally does not provide traditional flood insurance coverage.
That means homeowners should not assume that because they have homeowners insurance, they are automatically protected against flooding.
Flooding can occur from:
Rising water
Heavy rainfall
Storm surge
Overflowing rivers
Drainage issues
Other qualifying flood conditions
Depending on the property and circumstances, separate flood insurance may be appropriate.
A home does not have to be located in a traditionally recognized high-risk flood area for flooding to become a financial concern.
One of the most important concepts in homeowners insurance is understanding how a claim may be valued.
Replacement cost coverage is generally designed to pay the cost to repair or replace covered property without deducting depreciation, subject to the policy's terms, conditions, limits, and requirements.
Actual cash value generally takes depreciation into consideration when determining the value of covered property.
Consider a roof that is damaged by a covered event.
A homeowner may assume:
"My insurance will pay to replace my roof."
But the amount ultimately available can depend on the policy's valuation method, roof age, deductible, endorsements, applicable exclusions, policy conditions, and other factors.
Understanding the valuation method before a loss is much easier than learning about it after a loss.
A deductible is the amount you are generally responsible for paying before insurance responds to a covered loss, subject to the policy.
For example, if you have a $2,500 deductible and experience a qualifying covered loss of $20,000, the deductible generally represents the portion you would be responsible for before the applicable insurance payment.
But homeowners should also understand that some policies may contain different deductibles for different types of losses.
Depending on the policy and location, you may encounter:
Standard deductibles
Wind or hail deductibles
Hurricane deductibles
Percentage-based deductibles
Other special deductibles
Increasing a deductible may reduce your premium.
But it also increases the amount you may need to pay out of pocket following a covered loss.
The right question isn't simply:
"What's the cheapest policy?"
It should be:
"What combination of premium, deductible, limits, exclusions, and coverage provides the protection that makes sense for my situation?"
If you're purchasing a home, homeowners insurance is an important part of the transaction.
Your lender will generally require evidence of adequate insurance before closing on a financed property.
But insurance should not be treated as merely another box to check before closing.
It should be part of your home-buying strategy.
Before purchasing a property, consider:
Replacement cost
Roof age
Heating system
Electrical system
Plumbing
Property age
Construction type
Location
Flood exposure
Prior losses
Deductibles
Liability limits
Personal property
Additional structures
Available endorsements
Potential insurance eligibility issues
Overall premium
When you're determining what home you can afford, don't only look at the mortgage payment.
Your true housing expense may include:
Principal + Interest + Property Taxes + Homeowners Insurance + HOA/Condo Fees + Maintenance + Other Property Expenses
A home with a slightly lower purchase price can sometimes have substantially different insurance costs depending on the property's characteristics.
That is why insurance can be an important component of the home-buying conversation.
You don't have to wait until you buy another home to review your insurance.
Your insurance needs can change over time.
Consider reviewing your policy after:
Renovating your home
Adding a room
Finishing a basement
Building an addition
Installing a pool
Adding a detached structure
Purchasing expensive jewelry
Purchasing collectibles
Starting a home-based business
Acquiring expensive electronics
Getting married
Changing household occupancy
Installing major upgrades
Paying off your mortgage
Experiencing significant changes in your assets
Your insurance policy should evolve as your property and circumstances evolve.
A renovation can substantially change the value and characteristics of your home.
Consider a homeowner who purchases a property and later invests $150,000 into renovations.
The property may now have:
Higher-quality finishes
New flooring
Custom cabinetry
Updated electrical
New plumbing
New HVAC equipment
Finished living space
Higher-value personal property
Additional structures
If the insurance policy was never reviewed, the homeowner may not have the coverage structure they expect.
Tell your insurance professional about significant improvements.
Renovations can affect replacement-cost estimates, eligibility, endorsements, limits, and other policy considerations.
A higher-value property can create more complex insurance considerations.
Luxury homes may include:
Custom construction
High-end finishes
Architectural features
Expensive landscaping
Pools
Detached structures
Specialty equipment
Fine art
Jewelry
Collectibles
Wine collections
High-value furnishings
Home offices
Additional residences or properties
A standard homeowners policy may not automatically provide the level of protection a particular homeowner expects.
That is why high-value property owners should have a detailed conversation about limits, endorsements, valuation, liability exposure, and specialized property.
Homeowners with significant assets, multiple properties, rental properties, higher incomes, or increased liability exposure may want to consider an umbrella liability policy.
An umbrella policy can potentially provide additional liability protection above certain underlying insurance limits, subject to its terms and requirements.
For example, a homeowner may have:
Homeowners liability coverage
Auto liability coverage
Other underlying policies
An umbrella policy may provide additional protection above those underlying limits when applicable.
The purpose isn't simply to protect the house.
It is to help protect your broader financial position against covered liability claims.
Do you operate a business from your home?
This is an area where homeowners should be particularly careful.
Your homeowners policy may contain limitations or exclusions relating to business property, business activity, or business liability.
If you operate:
A consulting business
An online business
A professional practice
A contractor business
A photography business
A home-based retail operation
A short-term rental
Another business from your property
you should discuss the exposure with an insurance professional.
Never assume your homeowners policy automatically provides the coverage your business needs.
Not every property should be insured under the same type of policy.
A primary residence, vacation home, second home, rental property, and investment property can create very different insurance considerations.
Depending on the circumstances, different policy types or endorsements may be appropriate.
If you own multiple properties, an insurance review can help you evaluate:
Primary residence coverage
Secondary residences
Rental properties
Landlord exposures
Vacant properties
Seasonal properties
Liability protection
Umbrella coverage
Personal property
Building coverage
Loss of rental income
Other property-specific exposures
Insurance is not simply a commodity.
Two policies can have similar premiums while providing materially different coverage.
The difference may be found in:
Deductibles
Coverage limits
Exclusions
Endorsements
Valuation methods
Liability protection
Special coverage
Eligibility requirements
Policy conditions
That's why Brandon's approach is centered around education and strategy.
Rather than simply asking:
"How much do you want to pay?"
the conversation should begin with:
"What are we actually trying to protect?"
Brandon brings a unique perspective to the property insurance conversation because his professional experience extends across multiple areas of real estate.
As a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc., Brandon understands that insurance is one piece of a much larger property strategy.
His broader professional perspective includes experience involving:
Real Estate
Understanding the property transaction and the homeowner's goals.
Mortgage
Understanding how insurance fits into the financing and homeownership process.
Construction
Understanding how property condition, improvements, systems, materials, and renovations can affect the conversation.
Insurance
Understanding the importance of protecting the property, personal assets, and liability exposure.
That combination creates an opportunity to look at the property from more than one angle.
Instead of simply comparing premiums, let's look at the entire picture.
What type of home do you own?
How old is it?
What is the construction?
How old is the roof?
What major systems does it have?
Have you renovated?
Are there detached structures?
Do you have a pool?
Are there unique or high-value features?
What personal property needs protection?
Do you own valuable jewelry, art, collectibles, electronics, or other specialty items?
Do you have substantial financial assets that increase your liability exposure?
What could realistically go wrong?
Fire?
Wind?
Hail?
Water?
Theft?
Liability?
A serious accident?
A lawsuit?
A property becoming temporarily uninhabitable?
We'll look at the major components of your insurance, including:
Dwelling
Other structures
Personal property
Loss of use
Liability
Medical payments
Deductibles
Endorsements
Exclusions
Additional coverage considerations
The objective is to help you understand your options so you can make an informed decision about the coverage that fits your needs and budget.
The worst time to discover that your coverage isn't what you expected is after something goes wrong.
A roof doesn't wait until you're ready.
A pipe doesn't schedule an appointment before it bursts.
A fire doesn't ask whether you reviewed your policy.
And a lawsuit doesn't care whether you understood your liability limits.
Insurance is designed to be purchased before the loss—not understood afterward.
Take the opportunity to review your protection while you still have choices.
Your home represents years of work, investment, and financial commitment.
Your homeowners insurance should be more than a document your mortgage company requires.
It should be a deliberate part of your overall property protection strategy.
Whether you're:
Buying your first home
Purchasing your next home
Reviewing an existing policy
Renovating your property
Building your assets
Purchasing a second home
Owning multiple properties
Concerned about liability exposure
Looking for better coverage
Trying to understand your current policy
Brandon S. Broussard can help you understand the insurance conversation from a broader property perspective.
Don't just insure your house. Understand what you're protecting.
Contact Brandon S. Broussard, Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc., to discuss your homeowners insurance needs and explore available coverage options.
Real Estate. Mortgage. Insurance. Construction.
Because protecting a property starts with understanding the whole property.
Insurance coverage, premiums, deductibles, limits, eligibility, exclusions, endorsements, underwriting requirements, and policy terms vary by insurance company, policy form, property, applicant, and individual circumstances. Coverage is subject to the actual policy language, conditions, exclusions, limitations, and applicable underwriting guidelines. No coverage should be assumed based solely on this webpage.
This webpage is provided for general educational and informational purposes and does not constitute a guarantee of coverage, a representation that any particular loss will be covered, or legal, tax, or financial advice. Insurance products and availability are subject to applicable state law and insurance-company guidelines.
Brandon S. Broussard is a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc. Insurance services are provided through the applicable licensed insurance agency and are separate from any real estate, mortgage, construction, or other professional services provided through separate companies or entities.
Greater New England Area
Here to help with all of your insurance needs.
Sign in with your email address
Enter your email address
Please wait...
You’re being redirected to the page with listing data.