Mortgage Loan Originator — NMLS #1914798
Nextgen Mortgage Inc. — NMLS #1621958
Licensed in Massachusetts & New Hampshire
Massachusetts-Licensed Insurance Agent
LMI Insurance Agency Inc.
For a real estate agent, getting an offer accepted is only the beginning.
The real goal is:
That's where having the right professional partners can make a tremendous difference.
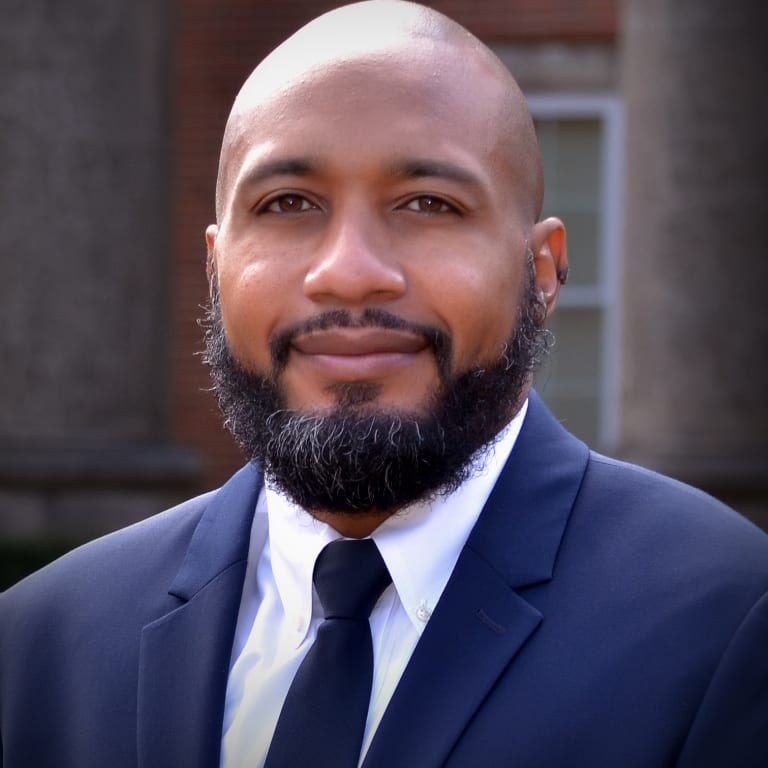
Brandon S. Broussard brings together mortgage lending and Massachusetts insurance experience to help real estate professionals move their buyers from preapproval to closing while addressing two critical components of the transaction: financing and property insurance.
The result is a more coordinated approach for the buyer—and a responsive resource for the real estate agent.
A preapproval is important.
But a successful real estate transaction requires much more than handing a buyer a preapproval letter and hoping everything works out.
Once your buyer gets an accepted offer, the transaction enters a much more detailed phase.
The lender may need:
Updated income documentation
Employment verification
Bank statements
Asset documentation
Identification
Tax returns
Business records
Letters of explanation
Documentation regarding debts
Documentation regarding deposits
Property information
Appraisal
Title information
Homeowners insurance
Additional underwriting conditions
And the buyer may need to make decisions regarding:
Loan program
Down payment
Closing costs
Interest-rate structure
Escrow
Insurance
Appraisal
Inspections
Closing funds
Brandon's job isn't simply to help your client apply for a mortgage.
When you're representing a buyer, you need to know what's happening with the financing.
You need someone who understands that your client's mortgage isn't happening in isolation.
It is happening inside a real estate transaction with deadlines.
There may be:
Purchase-and-sale deadlines
Financing deadlines
Appraisal deadlines
Inspection deadlines
Closing dates
Rate-lock considerations
Insurance requirements
Title requirements
Lender conditions
Seller expectations
A mortgage professional who understands the transaction can help keep the financing process moving while communicating with the appropriate parties.
NO SURPRISES.
NO AVOIDABLE DELAYS.
NO LAST-MINUTE SCRAMBLING.
NO “WE'RE STILL WAITING TO FIND OUT.”
Instead:
Before your client starts making offers, Brandon can help evaluate:
Income
Employment
Assets
Debts
Credit profile
Down payment
Closing-cost resources
Property type
Occupancy
Financing objectives
The objective is to understand what financing options may be appropriate before your client is under contract.
A strong preapproval can help your buyer understand their potential purchasing power and can give you, as the agent, important information when helping your client structure offers.
The process may include reviewing:
Income
Employment
Assets
Credit
Debts
Monthly obligations
Down-payment funds
Closing funds
Property considerations
The strength of the preapproval depends on the documentation reviewed and the lender's underwriting process.
KNOW BEFORE YOU OFFER.
Once your client finds the right property, financing needs to be considered alongside the purchase contract.
Brandon can work with the buyer and their real estate agent to understand the financing implications of the transaction, including considerations such as:
Purchase price
Down payment
Loan amount
Estimated payment
Property taxes
Homeowners insurance
Mortgage insurance where applicable
Closing costs
Seller concessions where permitted
Loan-program requirements
Appraisal considerations
It's about whether the entire transaction can successfully reach the closing table.
Once the offer is accepted, the mortgage application moves into the formal loan process.
The borrower provides the information and documentation required for processing and underwriting.
The lender then works through the applicable disclosure, verification, processing, appraisal, title, and underwriting requirements.
The mortgage file is organized and reviewed.
Brandon can help your client understand requests and keep the borrower focused on providing accurate documentation promptly.
This is where responsiveness matters.
The goal is to keep the file moving.
The property may need an appraisal depending on the loan program and transaction.
The appraisal helps the lender evaluate the property in accordance with the applicable lending requirements.
If appraisal issues arise, Brandon can help explain the financing implications and communicate with the appropriate parties.
This is where the loan file receives detailed underwriting review.
The underwriter may request additional documentation or clarification.
Brandon can help the borrower understand:
What is being requested
Why it is needed
How quickly it should be provided
What documentation may satisfy the request
Once the applicable underwriting conditions have been satisfied and the lender has approved the file for closing, the transaction moves toward its final stage.
This is one of the most important milestones for the buyer and the real estate agent.
But even after underwriting is complete, the transaction still needs to be properly coordinated through closing.
For most covered mortgage transactions, the buyer must receive the Closing Disclosure at least three business days before closing. The Closing Disclosure provides the final loan terms, projected payments, and closing costs.
Brandon can help the buyer understand the mortgage-related information and identify questions that should be addressed before closing.
At closing, the lender's funds and the buyer's required funds are coordinated through the settlement/closing process.
Once the applicable documents are signed, funds are disbursed, and the transaction is completed, ownership transfers according to the closing process.
Your buyer may have the income.
They may have the credit.
They may have the down payment.
They may have an accepted offer.
They may even have an appraisal.
But there is another critical part of the transaction:
Mortgage lenders generally require homeowners insurance as a condition of financing, and borrowers typically need to provide proof of coverage before the lender funds the mortgage.
That's where Brandon's insurance background can provide another useful resource.
As a Massachusetts-licensed insurance agent with LMI Insurance Agency Inc., Brandon can also help eligible Massachusetts clients address their homeowners insurance needs.
That can include helping clients evaluate:
Homeowners insurance
Dwelling coverage
Personal property coverage
Personal liability
Other structures
Additional living expenses
Deductibles
Replacement-cost considerations
Coverage limits
Available endorsements
Flood-insurance considerations
Umbrella-liability considerations
Property-specific insurance concerns
Massachusetts recognizes homeowners insurance as an important component of the residential real estate transaction, and an insurance binder may provide evidence of coverage while the insurer completes its underwriting process.
Your buyer may be ready to close.
But the lender may still need acceptable evidence of homeowners insurance.
Or the insurance company may identify an issue with the property.
Or the buyer may discover that the premium is materially different from what they expected.
Or the property may have characteristics that require additional consideration.
Those issues can create stress late in the transaction.
Once your buyer is under contract, insurance should be addressed as part of the closing process—not treated as a last-minute task.
The CFPB specifically recommends that homebuyers shop for homeowners insurance and provide the selected policy information to their loan officer so the lender can determine whether it meets its requirements.
Brandon can help your client work through both sides of the process in a coordinated manner.
Nextgen Mortgage Inc.
Mortgage Loan Originator:
Brandon S. Broussard
NMLS #1914798
Nextgen Mortgage Inc. — NMLS #1621958
Licensed in:
Massachusetts
New Hampshire
LMI Insurance Agency Inc.
Massachusetts-licensed Insurance Agent:
Brandon S. Broussard
Your job is to represent your client in the real estate transaction.
You should be able to focus on:
Finding the property
Analyzing the market
Negotiating the offer
Managing the transaction
Coordinating inspections
Communicating with your client
Working with the listing agent
Navigating the purchase contract
Getting to the closing table
Your mortgage partner should focus on the financing.
Your insurance partner should focus on the insurance.
Real estate transactions move quickly.
When your client has a question, the financing process shouldn't feel like a black box.
A good mortgage partner communicates with the appropriate parties while respecting privacy, authorization, lending regulations, and the borrower's confidential financial information.
Every transaction is different.
Income documentation.
Self-employment.
Credit questions.
Assets.
Property issues.
Appraisal concerns.
Insurance.
Underwriting conditions.
The objective is to identify potential obstacles and work through them appropriately.
The mortgage doesn't exist separately from the purchase.
The financing has to work within the contract and transaction timeline.
The goal is not simply:
“Get the loan approved eventually.”
The goal is:
Of course, closing dates can change because of circumstances outside the loan officer's control, including appraisal, title, borrower documentation, seller issues, underwriting, insurance, or other transaction requirements.
But having a professional actively managing the financing process can help reduce avoidable delays.
As an insurance agent, Brandon can help Massachusetts buyers evaluate the insurance side of their transaction while their mortgage is being processed.
That can help the buyer understand:
Homeowners insurance generally does not cover flood damage, so flood exposure should be considered separately when appropriate.
A vendor completes a task.
A partner understands the transaction.
Brandon's goal is to become a resource that real estate agents can confidently introduce to their buyers at the beginning of the process.
From:
“I'm thinking about buying a house.”
to:
“I'm preapproved.”
to:
“My offer was accepted.”
to:
“My loan is in underwriting.”
to:
“My insurance is in place.”
to:
“I'm clear to close.”
to:
Imagine your buyer finds their dream home.
You write the offer.
The offer is accepted.
Now the clock starts.
Instead of your client trying to figure out:
Who is my lender?
Who handles my insurance?
What documents do I need?
What is underwriting asking for?
What does my insurance company need?
What does my lender need?
When will the appraisal happen?
What happens next?
They have a dedicated mortgage professional who can help them understand the financing process and a Massachusetts-licensed insurance professional who can help address their homeowners insurance needs.
Real estate agents invest tremendous time building relationships.
You don't want your buyer's financing experience to undermine the confidence you've built.
A responsive mortgage professional can help reinforce your value as the real estate agent.
When the client says:
That's good for everyone.
A successful transaction requires coordination between multiple professionals.
Depending on the transaction, that can include:
Buyer
Real estate agent
Seller
Listing agent
Mortgage loan originator
Mortgage lender
Processor
Underwriter
Appraiser
Insurance agent
Insurance carrier
Closing attorney
Settlement agent
Title company
Home inspector
Other professionals
No single person controls every component.
When you introduce your buyer to Brandon, the conversation can begin with:
“Let's determine where you are today, what you're trying to accomplish, what financing may be appropriate, and what we need to do to put you in the strongest position possible for your purchase.”
Then:
Your reputation is built on results.
You want clients to remember:
You found them the home.
You negotiated the transaction.
You helped them navigate the process.
You connected them with professionals who performed.
And you helped them get to the closing table.
Brandon's role is to help you with the financing and insurance components that support that objective.
Mortgage Loan Originator with Nextgen Mortgage Inc.
NMLS #1914798
Massachusetts-licensed Insurance Agent with LMI Insurance Agency Inc.
An understanding of how financing and insurance fit into the real estate transaction.
A commitment to moving the buyer from preapproval toward closing.
An understanding that the mortgage, insurance, property, and transaction all have to work together.
When you have a buyer who needs financing, introduce them early.
Don't wait until after the offer is accepted.
Don't wait until the closing date is approaching.
Don't wait until an insurance problem appears.
Mortgage Loan Originator — NMLS #1914798
Nextgen Mortgage Inc. — NMLS #1621958
Licensed in Massachusetts & New Hampshire
Massachusetts-Licensed Insurance Agent
LMI Insurance Agency Inc.
Preapproval
Mortgage Planning
Loan Processing
Underwriting Coordination
Appraisal Coordination
Closing Preparation
Homeowners Insurance
Insurance Coordination
Transaction Communication
Real estate agents: connect your buyers with Brandon S. Broussard early in the process so they can begin addressing their financing and insurance needs before those issues become closing-day problems.
Mortgage financing is subject to credit approval, underwriting, income and asset verification, property requirements, loan-program guidelines, lender requirements, applicable laws and regulations, and other conditions. A preapproval is not a guarantee of final loan approval or funding. Closing dates are subject to the successful completion of all applicable transaction, lending, title, appraisal, insurance, underwriting, and contractual requirements.
Brandon S. Broussard, NMLS #1914798, is a Mortgage Loan Originator with Nextgen Mortgage Inc., NMLS #1621958, and is licensed in Massachusetts and New Hampshire.
Insurance services are provided separately through LMI Insurance Agency Inc. Brandon S. Broussard is licensed as an insurance agent in Massachusetts. Insurance coverage, premiums, deductibles, limits, eligibility, underwriting requirements, exclusions, endorsements, policy forms, and availability vary by carrier and individual circumstances. No particular insurance coverage or premium is guaranteed.
Homeowners insurance is generally required by mortgage lenders, and the borrower typically must provide acceptable evidence of coverage before the mortgage can be funded. Buyers may generally shop for their own homeowners insurance provider, subject to applicable lender requirements.
The mortgage and insurance businesses are separate services and separate legal entities. A borrower is not required to obtain insurance from a particular provider as a condition of receiving mortgage financing, except as otherwise permitted by applicable law and lender requirements.
Nothing on this page constitutes legal, tax, investment, financial-planning, or insurance-coverage advice. Consumers should review their individual circumstances with the appropriate licensed professional.
The goal is simple: help your clients get prepared, stay informed, address financing and insurance requirements, and work toward the closing date with a coordinated professional team.
Greater New England Area
Work with a licensed Insurance Agent and Certified Mortgage Planning Specialist and make sure your buyers are getting the best mortgage and insurance advice when purchasing their home.
Get The Best Partner, Contact Me ⬇
Sign in with your email address
Enter your email address
Please wait...
You’re being redirected to the page with listing data.