Your vehicle is one of the most important assets you use every day.
You rely on it to get to work, take your children to school, run your business errands, travel, visit family, and live your everyday life. But driving also creates risks that extend far beyond damage to your vehicle.
An accident can potentially result in:
Damage to your vehicle
Damage to another person's property
Injuries to other people
Medical expenses
Rental-car expenses
Legal expenses
Liability claims
Lost transportation
Significant out-of-pocket costs
That's why choosing auto insurance shouldn't be reduced to finding the lowest monthly premium.
The right question isn't simply, "How cheap can I insure my car?"
The better question is:
"How can I structure my personal auto insurance to provide appropriate protection while making the most of my overall insurance strategy?"
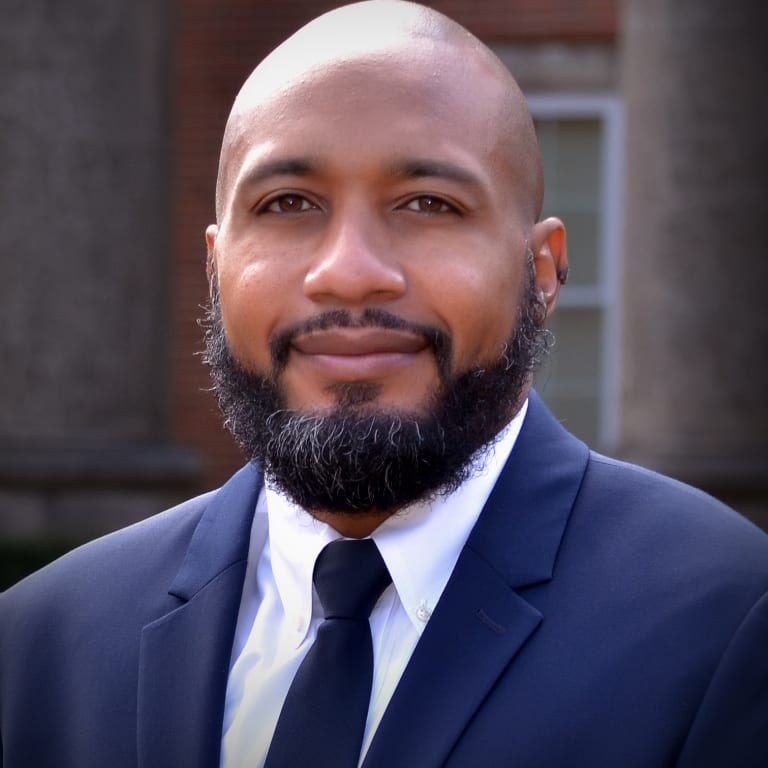
Brandon S. Broussard is a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc.
His approach is centered around helping clients understand their coverage, evaluate their risks, compare available options, and make informed insurance decisions.
And when it makes sense, that conversation can go beyond auto insurance.
Your home, automobiles, personal property, and liability exposure can all be part of one larger personal insurance strategy.
Personal auto insurance is designed to provide financial protection for covered losses and liabilities associated with owning and operating a vehicle for personal use.
Depending on the policy and applicable state requirements, personal auto insurance can include coverage for:
Bodily injury liability
Property damage liability
Personal injury protection or other required injury-related coverage
Uninsured motorist protection
Underinsured motorist protection
Collision
Comprehensive
Medical payments
Rental reimbursement
Towing and roadside assistance
Other optional coverage and endorsements
The exact coverages, limits, deductibles, exclusions, and requirements depend on the policy, insurance company, state law, and individual circumstances.
That's why an insurance review matters.
One of the most important components of auto insurance is liability coverage.
If you cause an accident and another person is injured or their property is damaged, you could potentially be financially responsible for covered damages.
Liability coverage can generally be divided into two major categories:
This coverage is generally designed to address covered bodily injury claims for which you are legally responsible, subject to the policy's limits and conditions.
A serious accident can result in:
Emergency medical treatment
Hospitalization
Rehabilitation
Lost wages
Long-term care
Legal claims
Significant financial damages
The cost of an accident can quickly exceed the minimum amount of insurance a driver carries.
Property damage liability generally applies to covered damage you cause to another person's property.
That could involve:
Another vehicle
A building
A fence
A utility structure
Landscaping
Other property
A vehicle accident isn't always simply about repairing two cars.
Your liability exposure can extend well beyond the vehicles involved.
Most states establish minimum insurance requirements.
But the legal minimum isn't necessarily the amount of protection that makes sense for your personal financial situation.
Consider two drivers.
One driver has relatively few assets and limited financial exposure.
Another owns a home, has substantial savings and investments, and has significant future income.
They may have very different reasons for selecting their insurance limits.
That's why Brandon's approach focuses on more than simply asking:
"What's the minimum I can legally carry?"
The better conversation is:
"How much financial exposure do I have, and how much protection makes sense for me?"
Collision coverage is generally designed to help pay for covered damage to your vehicle resulting from a collision, subject to the policy terms and deductible.
A collision could involve:
Another vehicle
A stationary object
A guardrail
A pole
A structure
Another covered collision scenario
Collision coverage can be especially important when your vehicle has significant value or when replacing the vehicle after an accident would create a substantial financial burden.
Comprehensive coverage generally addresses certain covered losses to your vehicle that aren't caused by a collision.
Depending on the policy, covered events may include things such as:
Theft
Vandalism
Fire
Falling objects
Certain weather-related damage
Animal strikes
Other covered causes of loss
For example, if a tree branch falls on your vehicle during a storm, that may be a comprehensive claim rather than a collision claim, depending on the circumstances and policy.
Your deductible represents an amount you are generally responsible for paying toward a covered loss before the applicable insurance coverage responds, subject to the policy.
Commonly, drivers may select different deductibles for:
Comprehensive coverage
Collision coverage
Other applicable coverages
A higher deductible can potentially reduce premium.
A lower deductible can potentially reduce the amount you pay out of pocket after a covered loss.
The question should be:
"What amount could I comfortably pay out of pocket following a covered loss?"
Your deductible should be consistent with your financial situation—not simply selected because it produces the lowest premium.
One of the most overlooked risks on the road is the other driver.
You can be a careful driver and still be involved in an accident caused by someone else.
That driver may have:
No insurance
Very low liability limits
Insufficient coverage for the injuries or damages involved
Depending on the policy and applicable state requirements, uninsured and underinsured motorist coverage can provide an important layer of protection.
This coverage can be especially important because you cannot control the amount of insurance another driver carries.
You can, however, evaluate the protection available under your own policy.
Depending on the state and policy, personal auto insurance may include or offer coverage designed to address certain medical expenses and injury-related losses.
The exact structure varies by jurisdiction and policy.
Depending on applicable law and coverage, these protections may address expenses associated with:
Medical treatment
Certain injury-related costs
Lost income
Passenger injuries
Other qualifying expenses
Because state requirements differ, your policy should be reviewed based on where you are insured and how you use your vehicle.
A covered accident can leave you without transportation for days—or potentially much longer.
Rental reimbursement coverage can potentially help pay qualifying rental-car expenses while your vehicle is being repaired following a covered loss, subject to the policy's limits and conditions.
Consider your daily life without your vehicle:
Getting to work
Taking children to school
Medical appointments
Shopping
Family obligations
Travel
Everyday transportation
For many families, rental coverage can be a relatively small consideration compared with the inconvenience of suddenly losing access to their primary vehicle.
Depending on the policy, roadside assistance may provide services for certain situations such as:
Towing
Flat tires
Battery issues
Lockouts
Fuel delivery
Other qualifying roadside events
Roadside assistance isn't a substitute for comprehensive insurance or mechanical coverage, but it can provide an additional convenience when unexpected problems occur.
Buying a new vehicle is an excellent time to review your insurance strategy.
A new vehicle may have:
A higher value
Different repair costs
Advanced safety technology
Specialized equipment
Financing requirements
Lease requirements
Different replacement considerations
If you finance or lease the vehicle, your lender or leasing company may also have specific insurance requirements.
Before driving away from the dealership, make sure your insurance arrangements have been properly addressed.
If your vehicle is financed or leased, your lender or leasing company generally has a financial interest in the vehicle.
That means they may have requirements concerning:
Physical damage coverage
Comprehensive coverage
Collision coverage
Deductibles
Liability limits
Additional insured/loss payee interests
Other policy requirements
Your insurance professional can help you understand how those requirements fit into your overall policy.
Many households have more than one vehicle.
You may have:
A primary vehicle
A second vehicle
A spouse's vehicle
A teenager's vehicle
A recreational vehicle
A seasonal vehicle
A newly purchased vehicle
When multiple vehicles and drivers are involved, the insurance conversation becomes more complicated.
That's where a comprehensive review can help.
Instead of looking at each vehicle independently, let's look at the household's overall exposure.
Adding a young driver to an auto policy can be one of the biggest changes to a household's insurance profile.
Parents should consider:
Driver experience
Vehicle selection
Liability limits
Discounts
Driver education
Household vehicles
Usage
Driving history
Applicable underwriting factors
The cheapest vehicle to purchase for a teenager isn't necessarily the cheapest vehicle to insure.
That's why it can be smart to discuss insurance before purchasing the vehicle.
Not every vehicle should necessarily be treated the same way.
If you own:
A luxury vehicle
A high-performance vehicle
A collector vehicle
A classic vehicle
A specialty vehicle
A modified vehicle
A custom vehicle
your insurance needs may differ from those of a standard personal automobile.
Specialized vehicles may require different coverage considerations, valuation methods, endorsements, or eligibility requirements.
Tell your insurance professional about modifications and specialty equipment.
Don't assume a standard auto policy automatically provides the coverage you expect for customized or high-value property.
A vehicle can depreciate quickly.
In some circumstances, the amount owed on an auto loan can be greater than the vehicle's current market value.
That creates a potential gap between:
What you owe
and
What the vehicle is worth.
Depending on the circumstances, loan/lease gap coverage may help address a qualifying difference between the vehicle's covered value and the remaining loan or lease balance.
Availability, eligibility, limitations, and how the coverage works vary.
If you're financing or leasing a newer vehicle, it's worth discussing.
Insurance isn't just about the vehicle.
It is also about how the vehicle is used.
Consider whether your vehicle is primarily used for:
Commuting
Personal use
School
Long-distance travel
Occasional business use
Ridesharing
Delivery
Multiple drivers
Other purposes
Changes in vehicle use can affect insurance considerations.
If your circumstances change, tell your insurance professional.
Insurance companies consider numerous factors when determining eligibility and premium.
Depending on the insurer and applicable law, factors can include:
Driving history
Claims history
Vehicle
Vehicle usage
Location
Mileage
Drivers
Coverage limits
Deductibles
Prior insurance
Vehicle characteristics
Other underwriting factors
This is why two drivers with similar vehicles may receive very different premiums.
We understand that everyone wants a competitive premium.
But the cheapest policy isn't necessarily the best value.
Imagine saving $30 per month and later discovering that you selected:
Lower liability limits
Higher deductibles
Less protection
Limited rental coverage
No appropriate protection for a major exposure
A lower premium isn't necessarily a lower financial risk.
That's the conversation Brandon wants to have with you.
If you own a home, your auto insurance shouldn't necessarily be viewed as a completely separate purchase.
Depending on eligibility, insurance-company availability, underwriting, and your individual circumstances, combining multiple personal insurance policies with the same insurance carrier may provide opportunities for multi-policy or bundle discounts and can simplify insurance management.
A bundled strategy may involve:
HOME + AUTO + UMBRELLA
And potentially other eligible personal-lines coverage.
1. Potential Multi-Policy Savings
Many insurers offer discounts when eligible policies are placed together.
The actual discount varies by carrier, policy, location, and underwriting.
2. Simplified Policy Management
Instead of managing several unrelated insurance relationships, eligible policies may be consolidated with one carrier.
3. Coordinated Coverage
A combined review can make it easier to identify potential gaps between your home, auto, and liability protection.
4. One Insurance Relationship
You have one place to turn when your personal insurance needs change.
5. Broader Liability Strategy
When homeowners and auto insurance are reviewed together, it becomes easier to evaluate whether your liability protection is consistent with your overall financial exposure.
Bundling isn't only about saving money.
It's about looking at your personal insurance portfolio as a whole.
Depending on your circumstances, your personal insurance strategy could include:
Your vehicles and driving-related liability.
Your dwelling, personal property, and homeowners liability.
Additional liability protection above certain underlying insurance limits, subject to policy terms and requirements.
Personal property and liability protection for eligible renters.
Coverage considerations for condominium owners.
Insurance for eligible vacation or secondary residences.
Protection for qualifying valuables and specialty property.
Additional coverage depending on your circumstances.
The objective isn't simply to put everything under one company.
The objective is to determine whether a coordinated insurance strategy makes sense for you.
Imagine reviewing your insurance in one conversation.
Instead of asking:
"How much is my car insurance?"
we can ask:
"What does my entire personal insurance picture look like?"
We can look at:
Your vehicles.
Your home.
Your belongings.
Your liability exposure.
Your deductibles.
Your coverage limits.
Your potential gaps.
Your available bundling opportunities.
That can produce a much more meaningful insurance review than simply comparing one auto premium against another.
Brandon's professional perspective goes beyond the insurance policy itself.
As a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc., Brandon helps clients evaluate their personal-lines insurance needs.
His broader professional experience across real estate, mortgage, construction, and insurance allows him to look at property from multiple perspectives.
Understanding the value and characteristics of the property you're trying to protect.
Understanding the insurance requirements and financial considerations associated with financed real estate.
Understanding that the condition, materials, systems, renovations, and improvements of a property can influence the insurance conversation.
Understanding how to evaluate coverage, limits, deductibles, exclusions, liability exposure, and available options.
One property. Multiple perspectives.
That's the advantage of having a professional who understands how these pieces can intersect.
Whether you're purchasing your first vehicle or managing multiple cars and properties, Brandon can help you take a broader look at your personal insurance needs.
We'll discuss:
Your vehicles
Drivers
Vehicle usage
Homeownership
Existing insurance
Coverage concerns
Financial considerations
We'll look at the areas that could potentially create significant financial exposure.
We'll examine:
Liability limits
Physical damage coverage
Deductibles
Uninsured/underinsured motorist protection
Rental coverage
Roadside assistance
Other applicable coverages
Depending on your circumstances and available insurance-company programs, we can discuss appropriate coverage options.
If you own a home or have other personal insurance needs, we can explore whether combining eligible policies may provide potential savings and a more coordinated insurance strategy.
The goal is to help you make an informed decision based on your coverage needs, risk exposure, budget, and available options.
You shouldn't need an insurance degree to understand your policy.
If you're not sure:
What your liability limits are
What your deductible is
Whether you have comprehensive coverage
Whether you have collision coverage
What happens if an uninsured driver hits you
Whether you have rental reimbursement
Whether your home and auto policies are properly coordinated
Whether you qualify for a multi-policy discount
Whether an umbrella policy makes sense
Whether your current coverage still fits your life
Let's review it.
You don't want to learn what your insurance covers by reading your policy from the side of the road after an accident.
You want to understand your protection before you need it.
Your circumstances change.
Your vehicle changes.
Your home changes.
Your income changes.
Your assets change.
Your family changes.
Your insurance strategy should change with them.
Whether you're looking for a new auto policy, replacing a vehicle, adding a driver, purchasing a home, reviewing your current coverage, or looking for a better way to coordinate your personal insurance, Brandon S. Broussard can help you evaluate the bigger picture.
Ask about your personal auto insurance options.
Ask about bundling your home and auto insurance.
Ask whether your current liability protection is appropriate for your financial situation.
Ask whether there are coverage gaps you may not know about.
Auto Insurance. Homeowners Insurance. Personal Property. Liability. Umbrella.
One conversation can help you understand how the pieces fit together.
Massachusetts-Licensed Property & Casualty Insurance Agent
LMI Insurance Agency Inc.
Let's review your coverage, explore your options, and determine whether a coordinated personal insurance strategy—including eligible home and auto bundling opportunities—makes sense for you.
Insurance coverage, premiums, deductibles, limits, eligibility, discounts, endorsements, exclusions, underwriting requirements, and policy terms vary by insurance company, policy form, state law, property, vehicle, driver, and individual circumstances. Multi-policy or bundled discounts are not guaranteed and are subject to carrier eligibility, underwriting guidelines, and applicable terms.
This webpage is provided for general educational and informational purposes and does not constitute a guarantee of coverage, premium, discount, claim payment, or policy eligibility. Coverage is governed by the actual insurance policy and applicable law. Specific coverage should be confirmed with the applicable insurance company and licensed insurance professional.
Brandon S. Broussard is a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc. Insurance services are provided through the applicable licensed insurance agency and are separate from any real estate, mortgage, construction, HVAC, or other professional services provided through separate companies or entities.
Greater New England Area
Here to help with all of your insurance needs.
Sign in with your email address
Enter your email address
Please wait...
You’re being redirected to the page with listing data.