Building a successful business takes years of hard work.
You invest your money, your time, your reputation, your employees, your equipment, your property, and your relationships with your customers.
But every business also faces risk.
A customer can slip and fall.
A contractor can damage a client's property.
A vehicle can be involved in an accident.
A fire can shut down your building.
A piece of equipment can fail.
A cyberattack can disrupt your operations.
An employee can be injured.
A professional service can result in a claim.
A lawsuit can threaten your company's financial position.
And a covered loss can potentially interrupt the income your business depends on.
Commercial insurance is designed to help businesses manage these risks.
But choosing commercial insurance shouldn't be about simply finding the cheapest policy.
It should be about understanding your business, identifying the risks you face, and building an insurance strategy around your actual operations.
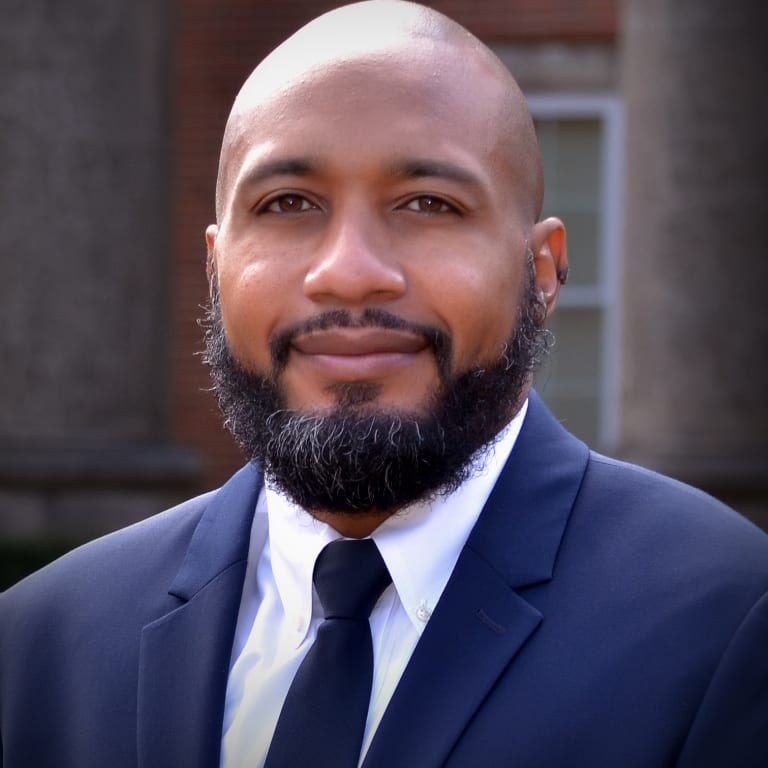
Brandon S. Broussard is a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc.
His approach is designed to help business owners understand their commercial insurance options and evaluate coverage based on the way their business actually operates.
Because your business isn't generic—and your insurance shouldn't be either.
Commercial insurance is a broad category of insurance products designed to help businesses manage financial risks associated with their property, operations, employees, vehicles, customers, products, professional services, and other exposures.
There is no single commercial insurance policy that automatically fits every business.
A restaurant has different risks than a construction company.
A medical office has different risks than a real estate brokerage.
A manufacturer has different exposures than a professional consultant.
A retail store has different needs than an apartment building owner.
A contractor has different insurance requirements than a technology company.
Before discussing coverage, it is important to understand:
What your company does
Where you operate
What property you own
What property you lease
Who works for you
What vehicles you use
What equipment you own
What services you provide
What products you sell
What contracts you sign
Who your customers are
What vendors you use
What your annual revenue looks like
What your potential liability exposures are
What could interrupt your business
The goal is to match your insurance strategy to your business—not force your business into a generic insurance package.
Depending on your business and circumstances, commercial insurance can include a wide range of coverage types.
Major commercial insurance categories can include:
Business Owners Policies
Commercial General Liability
Commercial Property
Business Income
Commercial Auto
Workers' Compensation
Professional Liability
Errors & Omissions
Directors & Officers Liability
Employment Practices Liability
Cyber Liability
Commercial Umbrella
Excess Liability
Inland Marine
Equipment Coverage
Contractor Insurance
Builders Risk
Product Liability
Liquor Liability
Commercial Crime
Businessowners Coverage
Surety Bonds
Employment-related coverage
Environmental Liability
Equipment Breakdown
Fiduciary Liability
Management Liability
Special Event Coverage
Vacant Property
Landlord/Commercial Real Estate Coverage
And other specialized commercial insurance solutions
Not every business needs every coverage.
The objective is to determine which risks are relevant to your particular operation.
A Businessowners Policy, commonly called a BOP, can combine several important types of commercial insurance into one package for eligible businesses.
A BOP may combine coverage such as:
Commercial property
General liability
Business income
Other applicable coverages or endorsements
BOP eligibility varies based on the business, industry, size, location, operations, revenue, property, and insurance-company underwriting requirements.
For an eligible small business, a BOP can provide a convenient way to address multiple exposures through one coordinated insurance package.
It may be appropriate for businesses such as:
Retail stores
Professional offices
Small contractors
Service businesses
Restaurants
Certain property owners
Other eligible small businesses
The important question is not:
"Do I need a BOP?"
It is:
"What risks does my business face, and what policy structure is appropriate for those risks?"
Commercial General Liability, commonly known as CGL, is one of the foundational coverages for many businesses.
It is generally designed to address certain third-party claims involving covered:
Bodily injury
Property damage
Personal and advertising injury
subject to the policy's terms, conditions, exclusions, and limits.
A customer enters your business.
They slip.
They fall.
They are injured.
They seek medical treatment and later bring a claim against your company.
General liability insurance may provide coverage for a qualifying claim, subject to the policy.
A business could potentially face claims involving:
Customers
Vendors
Visitors
Contractors
Property owners
Other third parties
That's why general liability is often a fundamental component of a commercial insurance strategy.
Your business may depend on significant physical assets.
Commercial property coverage can potentially protect covered business property against covered causes of loss.
Depending on the policy, this may include:
Buildings
Furniture
Fixtures
Equipment
Inventory
Machinery
Computers
Business personal property
Certain improvements and betterments
Other covered property
Imagine a fire damages your office.
Or a storm damages your building.
Or a covered loss destroys your inventory.
The financial impact could extend far beyond the cost of repairing the building.
You could also lose:
Equipment
Furniture
Inventory
Documents
Computers
Specialized tools
Other business property
Commercial property coverage can be an important part of protecting those assets.
This is one of the most important questions a business owner can ask.
If a covered loss damages your property and forces your business to temporarily shut down, you may still have:
Payroll
Rent
Utilities
Loan payments
Taxes
Vendor obligations
Insurance expenses
Other continuing costs
At the same time, your revenue may decline or stop.
Depending on the policy and circumstances, business income coverage may help replace certain lost income and/or continuing expenses resulting from a qualifying covered loss.
The specific coverage, waiting periods, limits, restoration periods, and conditions vary by policy.
The building may cost $500,000 to repair.
But what if your business loses $100,000 in revenue while the building is being repaired?
The interruption itself can become a major financial problem.
A business may need to spend additional money to continue operating after a covered loss.
For example, a business may need to:
Rent temporary space
Lease temporary equipment
Relocate operations
Pay additional transportation costs
Arrange alternative production
Implement temporary solutions
Depending on the policy, Extra Expense coverage may help with certain additional costs associated with continuing operations following a qualifying covered loss.
For some businesses, maintaining operations is critical.
If your company owns vehicles—or employees use vehicles for business purposes—you may need commercial auto insurance.
Commercial auto coverage can potentially apply to eligible vehicles and business-related driving exposures.
This can include:
Company vehicles
Work trucks
Vans
Service vehicles
Certain specialty vehicles
Business-owned vehicles
Potential coverage components may include:
Liability
Collision
Comprehensive
Uninsured/underinsured motorist coverage
Medical-related coverage where applicable
Hired and non-owned auto coverage
Other endorsements
A business may have employees or contractors using vehicles that the business does not own.
Depending on the circumstances, Hired and Non-Owned Auto Liability may provide protection for certain business-related auto liability exposures involving eligible hired or non-owned vehicles.
This can be particularly important for companies where employees regularly drive for business purposes.
If you have employees, workers' compensation can be a critical component of your insurance strategy.
Workers' compensation generally provides benefits for qualifying work-related injuries and illnesses, subject to applicable law and policy terms.
Requirements vary by state and circumstance.
Workers' compensation can address areas such as:
Medical expenses
Lost wages
Disability benefits
Other legally required benefits
It's also about protecting your employees and helping your business manage the financial consequences associated with workplace injuries.
If you employ people, workers' compensation should be part of the insurance conversation.
Some businesses don't manufacture products or operate large facilities.
They sell knowledge.
Advice.
Professional expertise.
Design.
Consulting.
Representation.
Professional services.
That creates a different type of liability exposure.
Professional Liability, often called Errors & Omissions (E&O) insurance, can potentially address certain claims alleging covered errors, omissions, negligence, or failure to perform professional services, subject to the policy.
This can be important for:
Consultants
Real estate professionals
Mortgage professionals
Accountants
Attorneys
Technology companies
Designers
Engineers
Architects
Marketing professionals
Other professional service businesses
A general liability policy isn't necessarily designed to replace professional liability coverage.
Companies and their directors and officers can face allegations related to management decisions.
Directors & Officers Liability, commonly called D&O, can provide protection for certain covered claims alleging wrongful acts in the management of a company, subject to the policy.
Potential exposures may involve:
Shareholders
Investors
Employees
Competitors
Regulators
Other third parties
D&O coverage can be particularly relevant to corporations, nonprofits, larger businesses, and organizations with boards or significant management responsibilities.
Employment-related disputes can become costly.
Businesses may face allegations involving:
Wrongful termination
Discrimination
Harassment
Retaliation
Failure to promote
Workplace-related employment practices
Employment Practices Liability Insurance (EPLI) can potentially provide protection for certain covered employment-related claims.
As a business grows and the number of employees increases, employment practices exposure can become increasingly important.
Your business may depend on:
Customer data
Employee information
Cloud software
Payment systems
Online accounts
Computer systems
Websites
Digital records
That creates cyber risk.
A cyber incident can involve:
Data breaches
Ransomware
Business interruption
Social engineering
Phishing
Network security incidents
Privacy claims
Notification expenses
Cyber extortion
Digital restoration
Cyber insurance can potentially provide coverage for certain qualifying cyber-related losses and liabilities, depending on the policy.
A restaurant has customer payment information.
A medical practice has sensitive patient information.
A real estate company has client data.
A contractor has customer information.
A professional office has confidential documents.
If your business uses technology or stores information, cyber risk deserves consideration.
A serious liability claim can potentially exceed the limits of your underlying insurance.
Commercial umbrella or excess liability coverage may provide additional liability protection above certain underlying insurance limits, subject to the policy.
This can be especially relevant for businesses with:
Significant assets
High revenue
Multiple locations
Large customer exposure
Commercial vehicles
Employees
High-value contracts
Substantial liability exposure
The goal is to provide an additional layer of protection when the underlying limits may not be enough.
Despite the name, inland marine insurance generally isn't about ocean transportation.
It can provide coverage for certain types of property that are transported, stored, installed, or used away from the primary business premises.
This can be particularly important for:
Contractors
Tradespeople
Equipment companies
Technology companies
Businesses transporting valuable equipment
Mobile operations
Examples can include:
Tools
Construction equipment
Specialized equipment
Computers
Installation equipment
Mobile business property
If your business property travels with you, inland marine coverage may deserve consideration.
Construction projects create unique exposures.
Builders risk coverage can potentially protect covered property during the construction or renovation process, subject to the policy.
Potentially covered property may include:
Structures under construction
Building materials
Certain equipment
Temporary structures
Other covered construction-related property
Coverage varies significantly by project and policy.
If you're constructing, renovating, or developing a property, insurance should be addressed before construction begins.
Contractors can face a combination of:
General liability exposure
Commercial auto exposure
Tools and equipment exposure
Employee exposure
Property exposure
Completed operations exposure
Contractual requirements
Subcontractor exposure
Construction-related risks
Depending on the trade, a contractor's insurance strategy may include:
General liability
Commercial auto
Workers' compensation
Inland marine
Equipment coverage
Umbrella/excess liability
Builders risk
Bonds
Other specialized coverage
A plumber doesn't have the same exposure as an electrical contractor.
An HVAC company doesn't have the same exposure as a general contractor.
A roofing contractor doesn't have the same exposure as a landscaper.
The operation matters.
Businesses that manufacture, distribute, import, or sell products can face product-related liability claims.
Product liability coverage can potentially address certain covered claims involving bodily injury or property damage allegedly caused by a covered product, subject to the policy.
Potentially exposed businesses include:
Manufacturers
Wholesalers
Distributors
Importers
Retailers
Food companies
Product designers
If your company puts products into the marketplace, product liability should be part of your risk conversation.
Businesses that sell, serve, furnish, or distribute alcoholic beverages may face exposures that are not necessarily addressed by standard general liability coverage.
Depending on the business and applicable law, Liquor Liability Insurance may be appropriate.
Potentially affected businesses include:
Restaurants
Bars
Taverns
Event venues
Caterers
Hospitality businesses
Other businesses involved in alcohol service
Coverage and legal requirements vary significantly by state and business operation.
Many businesses depend on equipment to operate.
Consider:
HVAC systems
Refrigeration
Boilers
Electrical equipment
Production machinery
Computers
Commercial kitchen equipment
Specialized systems
Equipment breakdown coverage can potentially address certain covered losses resulting from mechanical or electrical breakdown, subject to the policy.
For a business that depends heavily on equipment, a breakdown can create both a property problem and a business-income problem.
Crime exposures can include:
Employee theft
Forgery
Fraud
Computer fraud
Funds transfer fraud
Other covered criminal acts
Commercial crime insurance may provide coverage for certain qualifying losses.
This can be particularly important for businesses that:
Handle significant amounts of money
Have multiple employees
Conduct electronic payments
Manage customer funds
Maintain large inventories
Have multiple locations
Certain industries have environmental risks that may not be adequately addressed by standard liability coverage.
Examples can include:
Contractors
Manufacturers
Property owners
Industrial operations
Fuel-related businesses
Waste-related businesses
Certain cleaning operations
Environmental liability insurance can potentially provide specialized coverage for qualifying pollution-related exposures.
If you own commercial real estate, your insurance strategy can be very different from that of a business that simply leases office space.
Commercial property owners may need to consider:
Building coverage
General liability
Business income
Loss of rents
Equipment
Tenant improvements
Vacant property
Multiple locations
Contractors
Property management exposure
Umbrella/excess liability
If you own the building and operate a business inside it, both exposures should be evaluated.
Owning rental property creates unique insurance considerations.
Depending on the property and operation, coverage may address:
Building
Landlord liability
Rental income
Other structures
Property damage
Certain loss-of-income exposures
The appropriate policy depends on the type of property, occupancy, ownership structure, and operations.
A vacant property can have increased exposure to:
Vandalism
Theft
Water damage
Fire
Property deterioration
Liability
Standard commercial policies may have limitations or conditions relating to vacancy.
If your property is vacant, undergoing renovation, between tenants, or otherwise unoccupied, tell your insurance professional.
Certain businesses and contracts require bonds.
Depending on the business and project, this can include:
License bonds
Permit bonds
Contract bonds
Bid bonds
Performance bonds
Payment bonds
Other surety products
Bond requirements can vary significantly.
If a customer, government agency, general contractor, or other party requires a bond, it should be addressed as part of your overall business strategy.
Many businesses sign contracts requiring specific insurance provisions.
You may be asked to provide:
Certificate of insurance
Additional insured status
Specific liability limits
Waivers of subrogation
Primary and noncontributory wording
Commercial auto coverage
Workers' compensation
Umbrella limits
Other contractual requirements
Insurance requirements should be reviewed early.
A business may discover that its existing policy doesn't satisfy a new contract.
Before signing a significant contract, discuss the insurance requirements with your insurance professional.
A Certificate of Insurance, commonly called a COI, is often used to provide evidence of insurance coverage.
Customers, landlords, lenders, general contractors, property owners, and other parties may request certificates.
But a certificate is generally not the insurance policy itself.
The actual coverage is governed by the policy and applicable endorsements.
That's why it is important to make sure the underlying coverage actually meets the contractual requirement—not simply that a certificate can be produced.
A good commercial insurance strategy should begin with a simple question:
What would happen to your business if a major covered loss occurred tomorrow?
Could you:
Continue paying employees?
Keep your lease current?
Replace critical equipment?
Maintain customer relationships?
Operate from another location?
Replace inventory?
Continue servicing clients?
Survive a prolonged interruption?
Insurance is one component of risk management.
Business owners should also consider:
Emergency funds
Backup systems
Data backups
Vendor relationships
Business continuity plans
Disaster recovery
Succession planning
Cybersecurity
Contract management
The objective is not simply to insure your business. It is to make your business more prepared for the unexpected.
Having a commercial insurance policy doesn't automatically mean every risk is covered.
Your policy may contain:
Exclusions
Sublimits
Deductibles
Conditions
Coverage restrictions
Classification requirements
Endorsements
Reporting requirements
Other limitations
And your business may change after the policy is issued.
You hire employees.
You buy equipment.
You add vehicles.
You move locations.
You expand operations.
You start selling products.
You sign new contracts.
You acquire another company.
You begin working in another state.
Your insurance should be reviewed as your business evolves.
Starting a business is exciting.
But new businesses often overlook insurance until a customer asks:
"Can you send me your certificate of insurance?"
Or a landlord says:
"You need commercial liability coverage before you move in."
Or a lender requires:
"Provide evidence of property insurance."
Or a contract specifies:
"You must maintain $2 million of liability coverage."
Don't wait until someone else tells you what you need.
Start with your business model.
Then identify the risks.
Then build the appropriate insurance strategy.
If your company has grown, your insurance should be reviewed.
Consider a policy review if you've:
Increased revenue
Added employees
Purchased property
Added vehicles
Purchased equipment
Expanded into new locations
Added products
Started selling online
Signed larger contracts
Expanded services
Acquired another business
Started working with larger customers
Added subcontractors
Changed ownership
A policy that worked when you had five employees and $500,000 in revenue may not be appropriate after growing into a multimillion-dollar operation.
Commercial insurance works best when the insurance professional understands that a business is more than an insurance policy.
Brandon's broader professional experience provides multiple perspectives when discussing property and risk.
Understanding commercial and residential property ownership, transactions, property values, and real estate-related exposures.
Understanding the relationship between financing, collateral, property insurance, and lender requirements.
Understanding construction operations, contractors, renovations, building systems, equipment, and project-related exposures.
Understanding how commercial insurance can be structured around the risks your business actually faces.
One business. Multiple perspectives.
We'll discuss:
Industry
Services
Products
Locations
Employees
Revenue
Vehicles
Equipment
Property
Contracts
Customers
Vendors
Subcontractors
We'll look at potential exposure involving:
Property
Liability
Employees
Vehicles
Professional services
Cyber risk
Equipment
Business interruption
Products
Contracts
We'll examine your:
Policies
Limits
Deductibles
Exclusions
Endorsements
Certificates
Contractual requirements
Coverage gaps
Depending on your circumstances and available insurance-company programs, we can explore appropriate commercial insurance products.
The goal is to create an insurance structure that makes sense for your business, your risk profile, your contractual obligations, and your budget.
Commercial insurance can become complicated quickly.
The right professional can help you ask questions you may not have considered.
"What's my premium?"
Ask:
"What risks are we transferring to the insurance company?"
"Do I have general liability?"
Ask:
"What does my general liability policy actually cover—and what doesn't it cover?"
"Do I have business property insurance?"
Ask:
"Would my coverage be adequate to rebuild, replace equipment, replace inventory, and potentially continue operating after a covered loss?"
"Do I need an umbrella?"
Ask:
"How much liability exposure does my company have?"
That's the difference between purchasing insurance and developing an insurance strategy.
The worst time to discover an insurance gap is after the loss.
Before the accident.
Before the lawsuit.
Before the fire.
Before the cyberattack.
Before the employee injury.
Before the equipment failure.
Before the customer claim.
Let's identify the risks while you still have the opportunity to address them.
Your business represents more than a building, a bank account, or a balance sheet.
It represents:
Your investment.
Your employees.
Your customers.
Your reputation.
Your equipment.
Your property.
Your contracts.
Your income.
Your future.
Commercial insurance should be part of a larger strategy designed to help protect those interests.
Whether you're:
Starting a new business
Expanding an existing business
Purchasing commercial property
Leasing a new location
Hiring employees
Adding vehicles
Buying equipment
Signing a major contract
Expanding into a new market
Reviewing your existing coverage
Looking for more comprehensive protection
Trying to identify potential coverage gaps
Brandon S. Broussard can help you take a broader look at your commercial insurance needs.
Commercial Property. General Liability. Commercial Auto. Workers' Compensation. Professional Liability. Cyber. Umbrella. Business Income. Contractors. Commercial Real Estate. And More.
Don't wait until a loss forces you to discover what your insurance does—or doesn't—cover.
Contact Brandon S. Broussard, Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc., for a commercial insurance review.
Commercial insurance coverage, premiums, deductibles, limits, exclusions, endorsements, eligibility, underwriting requirements, policy forms, and availability vary by insurance company, business type, industry, location, operations, claims history, financial characteristics, and individual circumstances.
Not every coverage described on this webpage is appropriate or available for every business. The descriptions provided are general educational explanations and do not modify, expand, or replace the actual insurance policy. Coverage is subject to the terms, conditions, exclusions, definitions, limitations, and endorsements contained in the applicable policy.
Insurance requirements can also vary based on state law, contracts, lenders, landlords, customers, licensing authorities, and other parties. Businesses should review specific insurance requirements with their qualified insurance and legal professionals when appropriate.
This webpage does not guarantee coverage, eligibility, premium, claim payment, policy availability, or acceptance by any insurance company.
Brandon S. Broussard is a Massachusetts-licensed Property & Casualty Insurance Agent with LMI Insurance Agency Inc. Insurance services are provided through the applicable licensed insurance agency and are separate from any real estate, mortgage, construction, HVAC, or other professional services provided through separate companies or entities.
Greater New England Area
Here to help with all of your insurance needs.
Sign in with your email address
Enter your email address
Please wait...
You’re being redirected to the page with listing data.